• Skip to main content
  • Skip to primary sidebar

Collection Agency USA

collections

by

California Commercial Collection Agency for B2B Debt Recovery

California commercial collections are no longer just about how persistent a collector can be.

The more important question is:
What kind of commercial debt are we dealing with—and which California rules apply to it?

Since July 1, 2025, California has extended parts of its Rosenthal Fair Debt Collection Practices Act to certain defined small-business commercial credit debts of up to $500,000.

That does not mean every B2B invoice in California is treated the same way.

A Silicon Valley software invoice, a Los Angeles freight balance, a Central Valley equipment sale and a San Diego construction receivable can involve very different contracts, deadlines and recovery leverage.

CA-USA helps businesses recover commercial accounts throughout Los Angeles, San Francisco, San Diego, San Jose, Sacramento, Oakland, Fresno, Orange County and across California using professional negotiation, documentation analysis, debtor verification, bankruptcy screening, UCC-aware review and commercial credit reporting where appropriate.

The objective is straightforward:

Identify the strongest legitimate leverage first. Use legal escalation last.
California commercial collection agency helping businesses recover overdue B2B invoices across Los Angeles, San Francisco, San Diego and California

CA-USA provides a low cost, compliant, reputation-safe approach, equipped with all 50-state collections coverage, offering free credit reporting, free pre-litigation analysis, free bankruptcy scrubs, and zero onboarding fees. Secure – SOC 2 Type II compliant. Over 2,000 online reviews rate us 4.85 out of 5.  Over 20 years experience , delivering excellent B2B collection results.

You have direct cell phone access to one of our dedicated representatives, who is available whenever you need assistance

Need a Commercial Collection Agency in California: Contact Us

For our nationwide commercial recovery approach, see B2B Commercial Debt Recovery.


California Changed the Rules for Some Small-Business Debt

California’s Rosenthal Fair Debt Collection Practices Act historically focused primarily on consumer debt.

That changed for certain commercial credit transactions beginning July 1, 2025.

The expanded provisions can apply to defined covered commercial debt involving qualifying commercial credit transactions where the applicable amount is no more than $500,000.

This is important—but the distinction matters.

The law does not mean that every unpaid invoice between two corporations automatically becomes covered commercial debt.

That is why a California commercial collection file should begin with the transaction itself:

  • Was this trade credit?
  • A loan or commercial financing transaction?
  • A sale of goods?
  • Professional services?
  • Construction work?
  • Is the debtor an individual guarantor or a business entity?
  • When was the transaction entered into, renewed, sold or assigned?

In California, classification can matter almost as much as collection strategy.


One Invoice Can Have Three Different California Clocks

California does not have one universal limitation period for every commercial account.

Written Contracts — Generally Four Years

Actions based on written contracts, written obligations and many written account claims generally have a four-year limitation period.

Oral Contracts — Generally Two Years

A contract or obligation that is not founded on a written instrument can generally carry a shorter two-year limitation period.

Sales of Goods — Generally Four Years

California’s Commercial Code generally provides four years for breach of a contract for the sale of goods.

That can be particularly relevant to manufacturers, distributors, equipment vendors, agricultural suppliers and technology-hardware businesses.

The lesson is simple:

Do not determine a California deadline merely by looking at the invoice date. Determine what legal relationship created the receivable.

See our Statute of Limitations for Debt Collection resource for a broader discussion.


The Name on the Invoice May Not Be the Company That Owes You

California businesses frequently operate through:

  • LLCs
  • Corporations
  • Subsidiaries
  • DBAs
  • Trade names
  • Related operating companies

That can create trouble when a creditor knows the customer by its brand name rather than its registered legal entity.

California’s UCC requires particular accuracy when identifying registered organizations. A financing statement using only a debtor’s trade name is not sufficient.

Before relying on UCC leverage, we want to understand:

Which entity signed?
Which entity received the goods or services?
Which entity was invoiced?
Was there a security agreement?
Was the UCC filing made against the correct legal debtor?

That analysis can be far more valuable than simply increasing the number of collection calls.


California Construction Accounts Run on a Different Clock

Construction receivables deserve early attention.

For many California private projects, a direct contractor generally must record a mechanic’s lien before the earlier of:

  • 90 days after completion of the work, or
  • 60 days after the owner records a notice of completion or cessation.

For many subcontractors and suppliers, the deadline can shorten to 30 days after a notice of completion or cessation, subject to the applicable statutory requirements.

And there is another deadline after filing:

A California mechanic’s lien generally must be enforced within 90 days after it is recorded, unless a qualifying extension applies.

Sending an overdue construction invoice to collections does not automatically preserve lien rights.

For contractors, suppliers and equipment companies, the recovery strategy and lien calendar need to be considered separately.


A Dispute Should Be Defined, Not Allowed to Swallow the Account

California’s technology, manufacturing and professional-services markets generate complex invoices.

A customer may say:

“We dispute this balance.”

That statement should lead to another question:

Exactly which part?

If a customer owes $85,000 and can document a genuine dispute involving $12,000, there may be no commercial reason for the remaining $73,000 to remain frozen.

We review the contract, purchase order, invoices, acceptance records, correspondence, credits and payment history to separate:

Undisputed amount → documented dispute → unsupported withholding

That often creates a much cleaner negotiation path.


California Accounts We Commonly See Become Complex

California’s economy creates several recurring commercial collection patterns:

Technology & SaaS: accepted services, renewals, implementation disputes and multi-entity customers.

Manufacturing & Distribution: purchase orders, delivered goods, warranties, UCC issues and supply-chain balances.

Life Sciences & MedTech: specialized equipment, laboratories, research services and high-value vendors.

Agriculture & Food Processing: seasonal cash flow, equipment, packaging, freight and supplier credit.

Freight & Logistics: ports, warehousing, trucking, distribution and disputed shipment charges.

Construction & Trades: progress payments, retention disputes, material balances and rapidly moving lien deadlines.

Need to Recover an Unpaid Debt in California: Contact Us


Recent Recovery Results

California SaaS Account — 76% Recovered

A customer attempted to treat several months of accepted services as one large contract dispute after a corporate restructuring.

The file was reorganized by contracting entity, accepted service period and genuinely disputed credits. Instead of debating the entire balance with accounts payable, negotiations moved to the finance decision-maker responsible for the surviving entity.

Recovery: 76% of the placed balance without litigation.

Southern California Distributor — 69% Recovered

The debtor operated under a trade name while invoices and purchase records pointed to a separate legal LLC.

The recovery approach began with entity verification and document reconciliation, followed by bankruptcy and UCC review. Once responsibility was established, the undisputed balance was negotiated independently from a smaller product claim.

Recovery: 69% of the placed balance.


Recovery Economics: Our Fee Moves With the Result

CA-USA’s commercial collection model is designed so our compensation depends on successful recovery.

For most California B2B accounts, contingency rates typically range from 10% to 45%, depending on:

  • Balance size
  • Account age
  • Documentation
  • Complexity
  • Debtor condition

Larger balances and newer accounts generally receive lower contingency rates.

Pricing is communicated before placement.
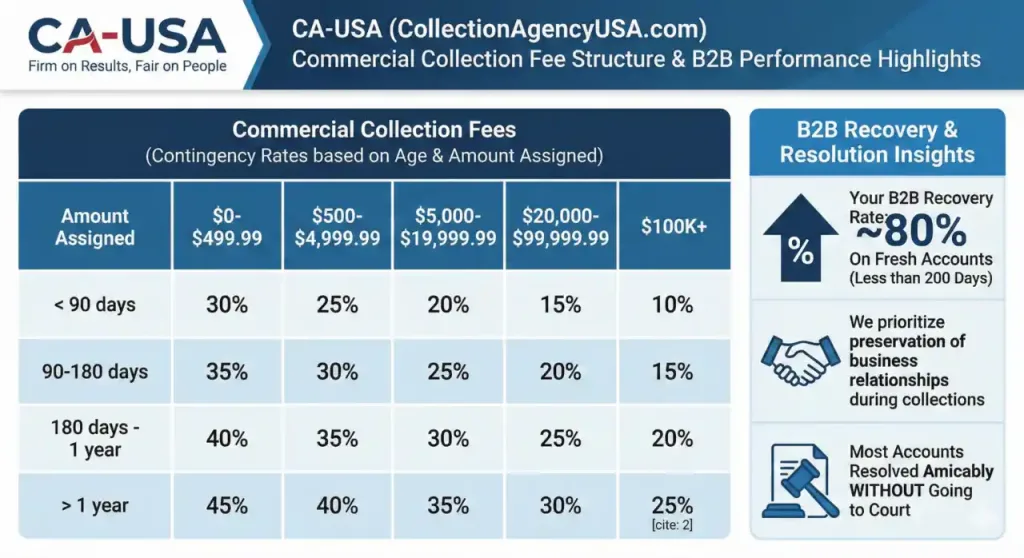
Commercial collection agency pricing is based on age and balance of the debt as shown on this image

For qualifying fresh commercial accounts under approximately 200 days old and supported by adequate documentation, CA-USA’s internal results can approach ~80% recovery.

That is not a guaranteed recovery rate. Actual results vary by account age, disputes, debtor condition, documentation and other circumstances.

See B2B Commercial Collection Agency Pricing for more information.


The CA-USA Escalation Model

We prefer a short escalation ladder rather than turning every file into a legal matter.

1. Establish the facts

Confirm the legal debtor, documentation, disputes, bankruptcy status and available commercial information.

2. Negotiate with the person who can authorize payment

That may be the CFO, owner, controller, finance director or accounts-payable manager.

Eligible accounts may also be considered for reporting to participating commercial credit bureaus where applicable requirements are satisfied.

3. Escalate only when economics justify it

Attorney referral is considered after reasonable non-legal recovery efforts fail, documentation supports the claim, escalation makes commercial sense and the client approves it.

CA-USA combines more than 20 years of collection experience with nationwide collection licensing coverage where required, SOC 2 Type II controls, dedicated support and reputation-conscious commercial negotiation.
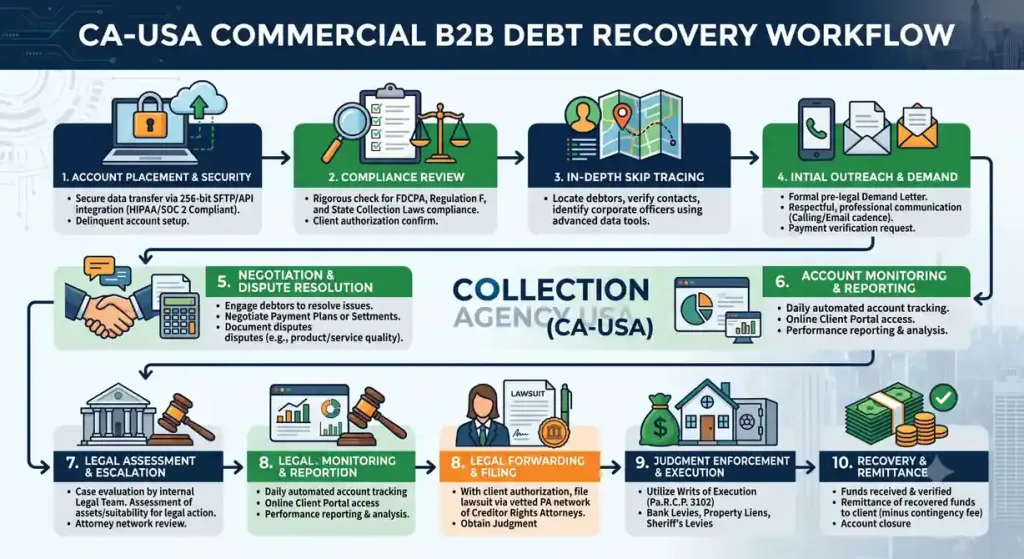
A 10-step flowchart infographic titled CA-USA Commercial B2B Debt Recovery Workflow detailing the debt collection process. Steps move sequentially from Account Placement & Security using 256-bit SFTP/API and SOC 2 compliance, through In-Depth Skip Tracing, Initial Outreach, and Negotiation. The process includes Legal Assessment, Legal Forwarding & Filing to obtain a judgment, and Judgment Enforcement using Writs of Execution and bank levies. The workflow concludes with Recovery & Remittance of funds. Each step has modern icons, process summaries, and regulatory references. The central logo shows Collection Agency USA (CA-USA)


California Commercial Collection FAQs

Does California’s Rosenthal Act now apply to business debt?

Beginning July 1, 2025, California expanded the Rosenthal Fair Debt Collection Practices Act to certain defined covered commercial debts. The expansion generally concerns qualifying commercial credit transactions of no more than $500,000 and applies to covered commercial credit or debt entered into, renewed, sold or assigned on or after July 1, 2025. It does not automatically mean every ordinary B2B trade invoice in California is covered, so the transaction should be classified before assuming the statute applies.

Is the California statute of limitations four years for every unpaid business invoice?

No. California generally provides four years for actions based on written contracts and certain written accounts, while obligations not founded on a written instrument can generally have a two-year period. Contracts for the sale of goods generally have a four-year period under California’s Commercial Code. The underlying transaction and accrual date should be reviewed before assuming a deadline.

My California customer uses a DBA. Which company should I send to collections?

Start with the legal entity that actually incurred the obligation. Review the contract, credit application, purchase order, invoices and acceptance records rather than relying solely on the customer’s trade name. This is especially important for secured transactions because a California UCC financing statement using only a debtor’s trade name does not sufficiently provide the debtor’s name.

Can a California contractor lose mechanic’s-lien rights while the invoice is being collected?

Yes. Collection activity does not stop California mechanic’s-lien deadlines. Depending on the claimant and whether a notice of completion or cessation was recorded, lien-recording deadlines can be considerably shorter than the ordinary contract limitation period. A recorded mechanic’s lien also generally must be enforced within 90 days after recordation unless a qualifying extension applies.

Can the owner of a California LLC be personally responsible for an unpaid company invoice?

Not merely because the person owns or manages the LLC. California generally treats an LLC’s obligations as liabilities of the company rather than its members or managers. Personal liability may arise in circumstances such as a written guarantee, another contractual undertaking, participation in wrongful conduct or a legally established alter-ego theory.

Can collection fees or attorney fees simply be added to a California commercial debt?

Not automatically. Additional fees must have a valid contractual or legal basis. California law also makes attorney-fee clauses in many contract actions reciprocal, meaning a provision written to benefit one contracting party can allow the prevailing party to recover reasonable attorney fees. Before adding collection expenses or representing that attorney fees are recoverable, the underlying agreement and applicable law should be reviewed.


Recover a California Commercial Account With the Facts on Your Side

California rewards creditors that understand the account before escalating it.

Before pursuing an overdue balance, ask:

What created the debt?
Which legal entity owes it?
Which deadline applies?
Is there a real dispute?
Is there secured or lien leverage that could expire?

CA-USA combines commercial negotiation, debtor verification, contract review, UCC-aware analysis, bankruptcy screening, commercial credit reporting where appropriate and measured legal escalation.

When you are ready to place accounts, see How to Assign Accounts to Collections.


A stock photo of a modern corporate building in Los Angeles where debt collectors are working on B2B debts

Professional enough to preserve the relationship. Persistent enough to recover the balance.

Need a Commercial Collection Agency? Contact Us

Serving Hundreds of Businesses !

Easy to use • Fully Compliant with Federal and State Laws • USA Citizens-Only Team • 24×7 Secure Portal • High Recovery Rates • Over 20 years Experience • Free Commercial Credit Bureau reporting • Low fee • Highly Rated !

Filed Under: collections

by

Florida Commercial Collection Agency for B2B Debt Recovery

Florida is one of the few states where commercial collections have their own regulatory framework.

That matters when a Miami distributor, Tampa contractor, Orlando professional-services firm or Jacksonville logistics company turns an unpaid invoice over to collections.

Florida does not treat every overdue account as the same problem.

A strong recovery strategy begins by identifying:

Who legally owes the money?

What created the debt?

Which Florida deadline applies?

What leverage still exists?

CA-USA helps recover overdue B2B accounts throughout Miami, Tampa, Orlando, Jacksonville, Fort Lauderdale, West Palm Beach, Naples, Sarasota and across Florida using professional negotiation, reputation safe methodology, contract and invoice review, business verification, bankruptcy screening, UCC-aware analysis and commercial credit reporting where appropriate.

The goal is to recover the balance without turning every commercial disagreement into litigation.

Attorney referral is considered only after reasonable non-legal recovery efforts fail, the documentation and economics justify escalation, and the client approves the next step.

Florida commercial collection agency helping businesses recover B2B debt across Miami, Tampa, Orlando and Jacksonville

CA-USA provides a low cost, compliant, reputation-safe approach, equipped with all 50-state collections coverage, offering free credit reporting, free pre-litigation checks, free bankruptcy scrubs, and zero onboarding fees. Secure – SOC 2 Type II compliant. Over 2,000 online reviews rate us 4.85 out of 5.  Over 20 years experience , delivering excellent B2B collection results.

You’ll be assigned a direct representative who is available by cell phone whenever you need support.

Need a Commercial Collection Agency in Florida? Contact us

For our nationwide approach, see B2B Commercial Debt Recovery.


Florida Has Specific Rules for Commercial Collection Agencies

Florida separates commercial collection activity from consumer collection regulation.

Under Florida’s Commercial Collection Practices Act, agencies operating as commercial collection agencies and subject to the statute generally must register with the Florida Office of Financial Regulation.

The current registration framework also requires a $50,000 surety bond for covered commercial collection agencies.

That is a meaningful distinction.

Commercial debt deserves commercial expertise—not consumer collection language copied onto a business account.

In Florida, the Contract Can Change the Clock

There is no single Florida deadline for every unpaid business invoice.

Written Agreements — Generally Five Years

Florida generally provides a five-year limitation period for actions based on a contract, obligation or liability founded on a written instrument.

Non-Written Agreements — Generally Four Years

Claims based on obligations that are not founded on a written instrument can generally have a four-year limitation period.

Sales of Goods — Generally Four Years

Commercial transactions involving the sale of goods generally fall under Florida’s UCC, which ordinarily provides a four-year period for breach of a sales contract.

That distinction matters for:

  • Equipment suppliers
  • Manufacturers
  • Wholesalers
  • Food distributors
  • Aviation suppliers
  • Marine suppliers
  • Industrial vendors

A creditor should therefore look beyond the invoice date.

What created the receivable can determine which deadline applies.

For a broader discussion, see our Statute of Limitations for Debt Collection guide.


The Customer’s Trade Name May Not Be the Legal Debtor

Florida businesses commonly operate through LLCs, corporations, subsidiaries, DBAs and related entities.

The name your sales department recognizes may not be the entity that actually signed the agreement.

Florida’s UCC is clear that a financing statement providing only a debtor’s trade name is not sufficient.

Before relying on secured-creditor leverage, we review questions such as:

Which entity signed the agreement?

Who received the goods or services?

Was a security agreement executed?

Was the UCC financing statement filed under the correct legal debtor name?

Is there a personal guarantee?

Correct entity identification can be more valuable than simply making more collection calls.


A Florida LLC Debt Is Usually the Company’s Debt

Florida law generally treats an LLC’s debts and liabilities as obligations of the company.

An owner or manager is not personally responsible merely because that person owns or manages the LLC.

A valid personal guarantee or another legally recognized basis for personal liability may change the result.

That means finding the owner is not enough.

The important question is:

Did that person personally agree to pay if the company did not?


Florida Construction Receivables Need Early Attention

Florida construction accounts operate on a much shorter lien calendar than an ordinary contract claim.

A Florida claim of lien generally must be recorded no later than 90 days after the lienor’s final furnishing of labor, services or materials.

And recording the lien is not the end of the process.

A Florida construction lien generally lasts one year after recording unless an enforcement action is commenced, although certain procedures can shorten the enforcement period.

Placing an overdue construction account with a collection agency does not automatically preserve lien rights.

That is particularly important for:

  • General contractors
  • Subcontractors
  • Restoration companies
  • HVAC contractors
  • Electrical contractors
  • Roofing companies
  • Material suppliers
  • Equipment-rental companies

Collection strategy and lien strategy should be reviewed together—but treated as separate deadlines.


Florida’s Commercial Economy Creates Different Types of Receivables

Logistics, Shipping & Distribution

Florida’s ports, warehouses, freight networks and distribution centers generate large volumes of B2B invoices involving transportation, storage, accessorial charges, equipment and delivered goods.

Aerospace, Aviation & Defense

Florida has more than 3,000 aerospace and aviation establishments, creating a significant ecosystem of manufacturers, MRO providers, engineering companies and specialized suppliers.

These accounts can involve purchase orders, inspection disputes, delivered components and high-value technical services.

Manufacturing

Manufacturers and industrial suppliers frequently need purchase-order, delivery, warranty and UCC documentation reviewed before a disputed balance can be resolved effectively.

Maritime

Ship repair, marine equipment, port services and commercial maritime businesses create specialized B2B accounts where the parties and contractual documents must be identified correctly.

Technology & Professional Services

Software, consulting, staffing, accounting and engineering companies often perform substantial work before payment becomes due.

A vague claim that “the work was not satisfactory” months later should be compared against approvals, acceptance history and earlier communications.

Construction & Restoration

Florida’s construction and property-restoration markets generate high-value receivables where payment disputes and lien deadlines often exist at the same time.


A Better Way to Handle a Partial Dispute

Suppose a Florida distributor is owed $96,000.

The customer later alleges that $14,000 of the delivered goods were defective.

That does not automatically explain why the remaining $82,000 has not been paid.

Instead of arguing over the entire balance, the account can be separated into:

Documented undisputed amount

Legitimate disputed amount

Unsupported withholding

This often changes the conversation from:

“We dispute the invoice.”

to:

“Why is the undisputed balance still unpaid?”

That is a much stronger commercial negotiation position.

Recent Florida Recovery Results

Jacksonville Commercial Account — 72% Recovery

A debtor was withholding payment across several invoices because of a dispute tied to one project.

The invoices were separated by project, the genuinely disputed portion was isolated, and negotiations moved from general accounts payable to the person responsible for financial approval.

Recovery: 72% of the placed balance without litigation.

South Florida Equipment Account — 67% Recovery

The customer was operating under a trade name while the contract and delivery records pointed to a separate Florida LLC.

Entity verification, document reconciliation and bankruptcy review established the responsible company before negotiations began.

Recovery: 67% of the placed balance.


Recovery Economics: We Succeed When You Recover

For most Florida commercial accounts, CA-USA works on a contingency basis.

There is no collection commission unless money is recovered.

Rates typically range from 10% to 45%, depending on:

  • Balance size
  • Account age
  • Documentation
  • Complexity
  • Debtor condition

Larger balances and younger accounts generally qualify for the lowest rates.

Pricing is confirmed before placement.

A chart showing B2B commercial collection agency fee, that varies by balance and age of debt.

For qualifying fresh commercial accounts under approximately 200 days old with adequate documentation, CA-USA’s internal results can approach ~80% recovery.

This is not a guaranteed recovery rate. Actual results vary according to account age, debtor condition, disputes, documentation and other factors.

See B2B Commercial Collection Agency Pricing for more information.


Before We Recommend an Attorney

Our preferred escalation path is deliberately commercial.

Verify the debtor.
Confirm the responsible legal entity and current operating status.

Review the documentation.
Contracts, purchase orders, invoices, delivery records, correspondence and guarantees tell us what can actually be supported.

Screen for bankruptcy.
A bankruptcy filing can immediately alter permissible collection activity.

Define the dispute.
A legitimate dispute involving one part of an account should not automatically freeze everything else.

Review UCC information where relevant.
Security interests and competing creditors can affect recovery leverage.

Negotiate with decision-makers.
Owners, CFOs, controllers and finance executives can often resolve balances that routine AP follow-up cannot.

Use commercial credit reporting where eligible.
Qualifying delinquent business accounts may be reportable to participating commercial credit bureaus when applicable requirements are satisfied.

Attorney referral comes last.

Legal escalation is considered only after reasonable recovery efforts fail and the client determines that the documentation, balance and economics justify it.

A 10-step flowchart infographic titled CA-USA Commercial B2B Debt Recovery Workflow detailing the debt collection process. Steps move sequentially from Account Placement & Security using 256-bit SFTP/API and SOC 2 compliance, through In-Depth Skip Tracing, Initial Outreach, and Negotiation. The process includes Legal Assessment, Legal Forwarding & Filing to obtain a judgment, and Judgment Enforcement using Writs of Execution and bank levies. The workflow concludes with Recovery & Remittance of funds. Each step has modern icons, process summaries, and regulatory references. The central logo shows Collection Agency USA (CA-USA)


Florida Commercial Collection FAQs

Does Florida require commercial collection agencies to register?

Yes. Florida has a specific Commercial Collection Practices Act. Commercial collection agencies subject to that law generally must register with the Florida Office of Financial Regulation and maintain the required registration. Florida’s current registration process also requires a $50,000 surety bond. Statutory exemptions exist, so applicability depends on the agency and its activities.

How long do I have to collect an unpaid Florida business invoice?

It depends on the obligation. Florida generally provides five years for actions founded on a written instrument and four years for obligations not founded on a written instrument. Contracts involving the sale of goods generally have a four-year period under Florida’s UCC. The agreement and transaction should be reviewed before assuming the applicable deadline.

Does Florida’s consumer collection law apply to ordinary B2B debt?

Pure commercial claims are treated differently from consumer debts. Florida has a separate Commercial Collection Practices Act specifically addressing commercial collection agencies and commercial claims. A commercial claim is generally one arising from credit used primarily for commercial rather than personal, family or household purposes.

My Florida customer uses a DBA. Which entity actually owes the invoice?

The responsible party should be determined from the contract, credit application, purchase order, invoices, delivery records and other transaction documents rather than relying solely on the trade name. This is especially important for secured transactions because Florida’s UCC states that a financing statement providing only the debtor’s trade name does not sufficiently provide the debtor’s name.

How quickly must a Florida construction lien be recorded?

A Florida claim of lien generally must be recorded no later than 90 days after the lienor’s final furnishing of labor, services or materials. A recorded lien generally must then be enforced within one year, although certain statutory procedures can shorten that period. Sending the debt to collections does not automatically preserve lien rights.

Can I pursue the owner of a Florida LLC for the company’s unpaid invoice?

Not simply because that person owns or manages the LLC. Florida generally treats an LLC’s debt as an obligation of the company. A personal guarantee or another legally recognized basis for personal liability can change the analysis, so the credit application, contract and guarantee documents should be reviewed.


Recover the Florida Account Before the Options Narrow

The best commercial collection strategy often starts before the account becomes seriously aged.

Ask:

Which company owes the money?

What documents support the balance?

Which Florida deadline is running?

Is any part of the balance genuinely disputed?

Is there UCC, lien or guarantee leverage?

CA-USA combines commercial negotiation, debtor verification, documentation review, bankruptcy screening, UCC-aware analysis, commercial credit reporting where appropriate and measured escalation.

When you are ready to place accounts, see How to Assign Accounts to Collections.


Firm on the balance. Professional with the people.

Need a Commercial Collection Agency? Contact Us

Serving Hundreds of Businesses !

Easy to use • Fully Compliant with Federal and State Laws • USA Citizens-Only Team • 24×7 Secure Portal • High Recovery Rates • Over 20 years Experience • Free Commercial Credit Bureau reporting • Low fee • Highly Rated !


Filed Under: collections

by

Commercial Lease Collection Agency for Broken Office Lease Debt

When a business tenant breaks a commercial lease, the balance is rarely just “unpaid rent.”

A landlord may be dealing with:

  • Past-due base rent
  • CAM or operating expenses
  • Property taxes
  • Utilities
  • Repair or restoration costs
  • Early-termination damages
  • Re-leasing expenses
  • Attorney fees where contractually and legally recoverable
  • A personal guaranty

The mistake is treating all of those charges as one unexplained number.

CA-USA helps commercial landlords, property managers and real-estate companies recover documented lease balances from former business tenants throughout the United States.

Our approach begins with the lease, ledger and loss calculation—not with aggressive collection pressure.

The objective is to determine:

What does the lease actually allow?

Who is legally responsible?

Which amounts are already due?

What credits or mitigation must be considered?

Is there a personal guarantor?

For our broader commercial recovery approach, see B2B Commercial Debt Recovery.

Commercial landlord reviewing broken office lease debt, CAM charges and guaranty documents with a commercial collection specialist


CA-USA provides a low cost, compliant, reputation-safe approach, equipped with all 50-state collections coverage, offering free credit reporting, free pre-litigation checks, free bankruptcy scrubs, and zero onboarding fees. Secure – SOC 2 Type II compliant. Over 2,000 online reviews rate us 4.85 out of 5.  Over 20 years experience , delivering excellent B2B collection results.

You’ll receive the direct mobile number of a dedicated representative, ensuring prompt support by call or text whenever you need assistance.

Need a Commercial Collection Agency? Contact us


Build the Claim From the Lease, Not Just the Rent Ledger

A strong commercial lease collection file should explain how the final balance was calculated.

That can include:

Base Rent
Past-due rent through surrender, termination or another relevant date.

Additional Rent
CAM, operating expenses, taxes, utilities or other charges authorized by the lease.

Physical Damage or Restoration
Documented costs associated with repairing or restoring the premises where the tenant is contractually responsible.

Security Deposit Credit
The final accounting should clearly show how any deposit was applied where permitted.

Future Lease Damages
These require more care. The lease language and applicable state law can affect acceleration, mitigation, re-leasing credits and the amount ultimately recoverable.

A clear claim is much easier to negotiate than a large unexplained demand.


The Personal Guaranty Can Completely Change the File

Many commercial tenants sign leases through an LLC or corporation.

If that company closes, the lease debt does not automatically become the owner’s personal debt.

But a personal guaranty can create a separate source of liability.

Before pursuing a guarantor, we want to review:

  • Who signed the guaranty
  • Whether it was signed personally
  • What obligations it covers
  • Whether liability is capped
  • Whether it decreases over time
  • Whether amendments affected it
  • Whether surrender language limits exposure

Commercial leases may contain a full guaranty, a limited guaranty, or in some markets a surrender-based or “good-guy” guaranty.

Those differences matter.

A collection strategy should be built around the guaranty that was actually signed—not merely the fact that an owner exists.


Can a Landlord Collect All Remaining Rent?

Sometimes—but this should never be assumed.

The answer can depend on:

  • Governing state law
  • Lease language
  • Acceleration provisions
  • Termination provisions
  • Mitigation requirements
  • When the premises were surrendered
  • Whether the space was re-leased
  • Replacement rent
  • Concessions given to the new tenant

A landlord may have a valid claim for future lease damages, but calculating that claim can be more complicated than:

monthly rent × months remaining

That is why CA-USA prefers a documented lease-loss calculation before pursuing a significant future-rent claim.

Re-Leasing Information Can Strengthen the Claim

When mitigation is relevant under the lease or governing law, good documentation matters.

Useful information may include:

  • Listing agreements
  • Broker correspondence
  • Marketing activity
  • Showing history
  • New lease commencement date
  • Replacement rent
  • Free-rent concessions
  • Tenant-improvement allowances
  • Brokerage expenses

This helps distinguish actual lease damages from amounts that may have been reduced after the space was reoccupied.

CAM, Taxes and Restoration Charges Need Documentation

Commercial lease disputes often become difficult because the former tenant says:

“I don’t agree with those extra charges.”

The best response is not simply repeating the balance.

It is showing how each charge was created.

For CAM or operating expenses, provide:

  • Lease provision
  • Tenant’s proportionate share
  • Reconciliation
  • Supporting calculation

For restoration or repairs, provide:

  • Move-out inspection
  • Photographs where available
  • Repair invoices
  • Contractor estimates or paid invoices
  • Lease provision establishing responsibility

Separating well-documented charges from genuinely disputed items often moves negotiations forward faster.


The Security Deposit Should Be Visible in the Accounting

A commercial security deposit should not disappear from the collection file.

Where applicable, the final accounting should clearly show:

Total documented charges
minus permitted security-deposit application
minus other credits
equals net amount placed for collection

This helps avoid a simple debtor objection:

“They already have my deposit.”

The collection agency should be able to explain the net claim.

What If the Tenant LLC Closed?

A closed LLC does not necessarily mean the collection file is over.

The first step is to determine what actually happened.

Did the business:

  • Shut down completely?
  • Sell its assets?
  • Change names?
  • Move operations to another entity?
  • Continue through a related company?
  • File bankruptcy?
  • Leave behind an enforceable guaranty?

Business verification can identify the current entity status and decision-makers.

But a related company or business owner should not automatically be treated as liable merely because operations appear connected.

Contractual liability must still be established.

Bankruptcy Changes the Collection Strategy Immediately

If the commercial tenant files bankruptcy, ordinary collection efforts against the debtor generally need to stop because of the federal automatic stay.

Commercial landlords can also face special bankruptcy rules concerning:

  • Lease assumption or rejection
  • Unpaid pre-bankruptcy rent
  • Post-petition obligations
  • Termination damages
  • Proofs of claim

Federal bankruptcy law also limits certain landlord claims for damages resulting from termination of a real-property lease.

That makes bankruptcy screening especially important before escalating an old commercial lease balance.

Two Commercial Lease Recovery Patterns

Office Tenant + Personal Guaranty

A tenant LLC closed and claimed there was nothing left to collect.

Instead of continuing to pursue an inactive company, the lease documents were reviewed and an enforceable personal guaranty identified. The claim was reorganized around documented rent, applicable credits and guaranty obligations before negotiations shifted to the responsible guarantor.

Use an actual verified CA-USA recovery percentage here.

Lease Balance + CAM Dispute

A former tenant disputed an entire balance because it disagreed with year-end CAM charges.

The claim was separated into past-due base rent, documented CAM, restoration costs and disputed adjustments. Negotiations focused first on the undisputed portion instead of allowing one CAM disagreement to freeze the entire account.

Use an actual verified CA-USA recovery percentage here.


Performance-Based Commercial Lease Recovery

CA-USA generally handles commercial collection accounts on a contingency basis.

You pay a collection commission when money is successfully recovered.

Commercial contingency rates typically range from 10% to 45%, depending on factors such as:

  • Balance size
  • Account age
  • Documentation
  • Complexity
  • Debtor condition

Higher balances and newer accounts generally qualify for lower rates.

A chart showing B2B commercial collection agency fee, that varies by balance and age of debt.

For qualifying fresh commercial accounts under approximately 200 days old with strong documentation, CA-USA’s internal results can approach ~80% recovery.

Results vary substantially by account and are not guaranteed.

See B2B Commercial Collection Agency Pricing for more information.


What to Send With a Broken Commercial Lease Account

A strong placement package usually includes:

  • Signed lease
  • Lease amendments
  • Personal guaranty
  • Rent ledger
  • Default notices
  • Termination or surrender correspondence
  • Security-deposit accounting
  • CAM reconciliations
  • Tax or utility allocations
  • Repair and restoration invoices
  • Move-out inspection documentation
  • Re-leasing information
  • Payment history
  • Relevant tenant or guarantor correspondence

Better documentation can mean fewer disputes and faster commercial negotiations.

Our Escalation Approach

CA-USA begins with commercial recovery rather than litigation.

Review the claim.
Understand the lease, ledger, guaranty and supporting charges.

Verify the debtor.
Confirm the tenant entity, guarantor and current business status.

Check bankruptcy.
A bankruptcy filing can immediately change permissible collection activity.

Define disputes.
Separate legitimate disagreements from undisputed rent or charges.

Negotiate professionally.
Reach the person with authority to resolve the account.

Use commercial credit reporting where appropriate.
Eligible B2B accounts may be reportable to participating commercial credit bureaus when applicable requirements are satisfied.

Attorney referral comes last.

Legal escalation is considered only when reasonable collection efforts have failed, the documentation and economics support further action, and the client approves it.


Commercial Lease Collection FAQs

Can a landlord collect the remaining rent after a business breaks a commercial lease?

Potentially, but not automatically in every case. The recoverable amount depends on the lease language, applicable state law, whether future rent may be accelerated, the landlord’s mitigation obligations, re-leasing activity, security deposits and other credits. A commercial lease claim should be calculated from the actual lease and loss history rather than simply multiplying monthly rent by the months remaining.

Does a commercial landlord have to find a new tenant before collecting future rent?

That depends on the governing state law and the lease. Some jurisdictions impose a duty to mitigate damages, while the timing and effect of re-leasing can differ. A landlord should document marketing, re-leasing efforts, replacement rent, concessions and the date the premises were reoccupied before calculating a remaining lease claim.

Can a landlord pursue the business owner personally if the tenant LLC closes?

Not merely because the person owned or managed the tenant company. Personal liability may exist if the owner signed an enforceable personal guaranty or another legally recognized basis for individual liability applies. The guaranty should be reviewed for its scope, dollar cap, duration, amendments and any surrender or good-guy provisions before collection begins.

Can CAM charges, taxes, utilities and repair costs be sent to collections after a commercial tenant leaves?

They may be recoverable when the lease makes the tenant responsible and the amounts can be supported. The collection file should include CAM reconciliations, tax or utility allocations, repair invoices, inspection records, restoration charges and the lease provisions authorizing those amounts. Unsupported estimates can make an otherwise strong lease claim harder to resolve.

Should the security deposit be applied before a commercial lease balance goes to collections?

The lease and applicable state law should control how the deposit is handled. As a practical accounting matter, the landlord should clearly show the deposit and any permitted application of it when preparing the final ledger so the collection agency is pursuing the documented net balance rather than an unexplained gross figure.

What happens to commercial lease debt if the tenant files bankruptcy?

A bankruptcy filing generally triggers the federal automatic stay, which can stop collection activity against the debtor for pre-bankruptcy claims. Commercial lease claims can also be affected by bankruptcy rules governing assumption or rejection of leases and the statutory cap on certain landlord termination damages. The account should be reviewed for bankruptcy status before further collection activity.

When should a broken commercial lease be sent to a collection agency?

Early review is useful when the tenant has surrendered the premises, stopped responding, repeatedly broken payment promises, dissolved or changed entities, disputed charges after move-out, or appears financially distressed. The landlord does not need to wait until every possible future charge has accumulated if a well-documented current balance is already due, although future damages should be handled according to the lease and applicable law.

What documents should a landlord provide for commercial lease collections?

A strong file typically includes the signed lease and amendments, personal guaranty, rent ledger, default and termination notices, security-deposit accounting, CAM or operating-expense reconciliations, repair and restoration invoices, surrender correspondence, inspection records, re-leasing information, payment history and relevant communications with the tenant or guarantor.


Recover the Lease Balance With the Documents Behind It

A broken commercial lease can create a substantial receivable.

But the strongest claim is not necessarily the largest number on the landlord’s spreadsheet.

It is the amount that can be explained, documented and tied directly to the lease.

CA-USA helps landlords and property managers recover commercial lease debt through documentation review, business verification, bankruptcy screening, professional negotiation and measured escalation.

For nationwide commercial collections, see B2B Commercial Debt Recovery.

When you are ready to place the account, see How to Assign Accounts to Collections.


Recover the documented balance. Preserve leverage. Escalate only when it makes commercial sense.

Need a Collection Agency? Contact us


Filed Under: collections

by

Commercial Collection Agency: ~80% Recovery on Newer Debt

Your business is not a charity.

Need help recovering unpaid business invoices? CA-USA is a nationwide commercial collection agency specializing in B2B debt recovery for companies that delivered the product, completed the work, or honored the contract—and still have not been paid.

Our commercial recovery process combines contract and invoice review, business verification, bankruptcy screening, skip tracing, UCC-aware account review, reputation-safe negotiation, and commercial credit reporting where eligible.

Attorney referral is considered only after reasonable collection and negotiation efforts have failed and the account supports further escalation. Any legal action is pursued only with your written authorization. A 4.85★ Google rating reflects our commitment to professional service and client support.

Recover past-due B2B invoices with professional commercial debt recovery. CA-USA offers business credit reporting, negotiation-first collections, and nationwide support.

We collect debt every day. Our commercial collectors use persistence, experience, and proven recovery tools to get you paid.

Contingency-based: You pay only when we recover. No recovery, no fee.

Direct support: You get cell phone access to a dedicated representative whenever you need help.

Ready to assign overdue accounts? Connect with us now

CA-USA provides nationwide collection coverage with required licenses, registrations, and bonds, a SOC 2 Type II secure environment, dedicated support, and 20+ years of collection experience.

What Is B2B Commercial Debt Collection?

Commercial debt collection is the recovery of money owed from one business to another business.

Typical accounts include:

  • Unpaid invoices for goods or materials
  • SaaS and software subscriptions
  • Freight and logistics balances
  • Professional-service fees
  • Equipment rentals and leases
  • Construction and subcontractor accounts
  • Manufacturing and supplier receivables
  • Commercial property obligations
  • Staffing and consulting invoices
  • Restoration and contractor balances

Business debt is not simply consumer debt with a larger balance.

B2B accounts may involve contracts, purchase orders, corporate entities, personal guarantees, security interests, UCC filings, payment disputes and valuable ongoing customer relationships.

B2B Collections Work Differently From Consumer Collections

The FDCPA Generally Does Not Cover Business Debt

The federal FDCPA primarily governs debts incurred for personal, family or household purposes. Ordinary business debts generally fall outside its scope.

Commercial collections can still be subject to state laws, licensing requirements, contract law, bankruptcy rules, UCC provisions and other applicable requirements.

Reputation Matters in B2B

Your delinquent customer may still be a major buyer, distributor, referral source or long-term client.

Recovering one invoice should not unnecessarily destroy years of future business.

That is why CA-USA uses reputation-safe collection tactics—firm on the balance, but professional with the people.

When Should a B2B Account Go to Collections?

There is no universal rule that every account must reach exactly 90 days before placement.

Consider outside collection when:

  • Repeated reminders produce no meaningful response
  • Payment promises are repeatedly broken
  • Accounts payable stops responding
  • A payment plan defaults
  • A previously accepted invoice suddenly becomes “disputed”
  • The debtor appears to be experiencing financial trouble
  • The outstanding balance creates meaningful cash-flow risk
  • An important contractual or legal deadline is approaching

For many companies, 60–90 days past due is a reasonable escalation point, but behavior and risk can justify earlier action.

A $100,000 customer that suddenly disappears may deserve attention long before day 90.

What Should Be Sent With a Commercial Collection Account?

A strong commercial file should show:

What was agreed → what was delivered → what became due → what remains unpaid.

Useful documents include:

  • Contracts and credit applications
  • Invoices and statements
  • Purchase orders
  • Proof of delivery or completion
  • Payment history
  • Emails and account correspondence
  • Dispute documentation
  • Personal guarantees
  • Security agreements
  • Relevant UCC information
  • Prior payment plans or settlements

Good documentation limits the debtor’s ability to create confusion later.

The CA-USA Commercial Recovery Framework

Step 1: Contract, Invoice & Account Review

We review the available contracts, invoices, purchase orders, guarantees, statements and dispute history before collection strategy is chosen.

We also confirm the correct debtor entity—particularly important when businesses operate through several LLCs, subsidiaries or DBAs.

Step 2: Bankruptcy Screening & Business Verification

Before escalation, we screen for bankruptcy and verify relevant business information.

Available records may help identify:

  • Corporate status
  • Current business addresses
  • Ownership information
  • Operating status
  • Relevant public records
  • Available UCC information

The goal is to understand who owes the money and what recovery path is realistic.

Step 3: Reputation-Safe Business Outreach

Commercial collection works best when the right person is contacted.

Depending on the debtor, that may be accounts payable, the controller, CFO, finance director, owner or senior management.

Our communication is professional, persistent and focused on resolution—not unnecessary confrontation.

Step 4: Dispute Resolution & Negotiation

B2B debts frequently involve disputes over pricing, delivery, scope, credits, quality or contract terms.

We identify the actual dispute and separate legitimate issues from simple delay.

Sometimes only part of an invoice is disputed.

Separating undisputed amounts from disputed amounts can unlock payments that would otherwise remain frozen.

When appropriate, payment arrangements or negotiated resolutions may be considered with client authority.

Step 5: Commercial Credit Reporting — Where Eligible

Eligible delinquent business accounts may be reportable to participating commercial credit bureaus.

Commercial credit reporting provides an important non-legal recovery tool because payment behavior can influence how lenders, vendors and other businesses evaluate a company’s creditworthiness.

  • Dun & Bradstreet (D&B)

  • Experian Business

  • Equifax Business

Step 6: Management Review

Before any legal recommendation, we review documentation strength, debtor status, prior negotiations, collectability and the economics of further action.

Step 7: Attorney Referral — Only as a Last Resort

Legal action is not the default collection strategy.

Attorney referral is considered only when reasonable non-legal collection efforts have failed and the balance, documentation and likelihood of recovery justify escalation.

The client remains involved in that decision.

A 10-step flowchart infographic titled CA-USA Commercial B2B Debt Recovery Workflow detailing the debt collection process. Steps move sequentially from Account Placement & Security using 256-bit SFTP/API and SOC 2 compliance, through In-Depth Skip Tracing, Initial Outreach, and Negotiation. The process includes Legal Assessment, Legal Forwarding & Filing to obtain a judgment, and Judgment Enforcement using Writs of Execution and bank levies. The workflow concludes with Recovery & Remittance of funds. Each step has modern icons, process summaries, and regulatory references. The central logo shows Collection Agency USA (CA-USA)

Why UCC Information Can Matter

The Uniform Commercial Code can become important when a transaction involves:

  • Equipment
  • Inventory
  • Goods
  • Accounts receivable
  • Secured financing
  • Other business collateral

A UCC filing does not tell us whether a debtor has cash available.

It may, however, reveal security interests claimed by other creditors.

That can materially affect collection strategy when several creditors are competing for the same assets.

CA-USA therefore reviews relevant contracts, guarantees, security agreements and available UCC information before assuming secured-creditor leverage exists.

Personal Guarantees Can Change the Recovery Path

An unpaid corporate invoice does not automatically make an LLC member or corporate owner personally liable.

But a properly executed and enforceable personal guarantee may create an additional obligation.

That can become particularly important if the operating company:

  • Stops trading
  • Has few assets
  • Dissolves
  • Files bankruptcy

Guarantees should therefore be identified early rather than discovered after months of unsuccessful collection activity.

Recent Commercial Recovery Scenarios

Contract Dispute Resolved Without Legal Action
A commercial construction materials supplier placed a $64,500 account after a regional general contractor withheld payment, disputing delivery milestones and material spec variances. Rather than immediately escalating the account to court, our team reviewed the signed purchase orders, proof-of-delivery tickets, and change-order correspondence, isolating the valid scope adjustment from the undisputed balance. After direct, structured negotiations with the debtor’s CFO, $56,000 (87%) was recovered in 34 days without attorney involvement.

What mattered: Comprehensive documentation and targeted mediation created faster leverage than an immediate lawsuit threat.

Business Had Stopped Responding — Verification Changed the Strategy
A wholesale distribution firm placed a $42,800 past-due account after broken payment promises turned into complete radio silence. Corporate entity verification, bankruptcy screening, and asset discovery revealed that while the original trade name was dormant, the principal had transitioned operations under a newly registered operating entity at an active distribution warehouse. Using this operational intelligence, we re-established contact directly with the managing partner, securing a $38,500 (90%) structured settlement paid out over 60 days.

What mattered: The account required more than another routine demand letter. Identifying the debtor’s active business operations changed the entire recovery path.

What If the Debtor Files Bankruptcy?

A bankruptcy filing generally creates an automatic stay that stops ordinary collection activity against the debtor for pre-bankruptcy obligations.

The creditor may instead need to participate in the bankruptcy process, including filing a proof of claim where appropriate.

That is why bankruptcy screening happens before escalation.

A business bankruptcy also does not automatically resolve every related issue. Separate guarantors or other liable parties may require individual review.

Nationwide Commercial Collections

Modern B2B transactions frequently cross state lines.

Your company may be in one state, the customer in another, the contract governed by another state’s law, and the guarantor located somewhere else entirely.

State collection requirements, limitation periods, contract rules and litigation procedures can vary.

CA-USA maintains nationwide collection licensing coverage, including required licenses, registrations and bonds, allowing businesses with customers across the United States to use one commercial recovery partner. We see nearly an 80% recovery rate on newer debt that is viable and assigned around 90 Days.

A chart showing B2B commercial collection agency fee, that varies by balance and age of debt.

Industries We Serve

Technology & SaaS

Subscription, licensing, implementation and enterprise software balances.

Logistics, Freight & Transportation

Freight invoices, carrier balances, warehouse charges and transportation receivables.

Manufacturing & Distribution

Inventory, components, wholesale goods, equipment and trade-credit accounts.

Construction & Trades

Subcontractor, material-supplier, equipment-rental and project balances.

Professional Services

Consulting, staffing, accounting, marketing, engineering and IT invoices.

Commercial Real Estate & Property Services

Commercial tenant obligations, property services and business lease balances.

Restoration & Contractors

Water, fire, remediation, reconstruction and commercial restoration invoices.

Agriculture & Farm Supply

Equipment, fertilizer, feed, seed and other commercial agricultural balances.

Life Sciences & Healthcare Vendors

B2B laboratory, pharmaceutical, medical-device and healthcare-supplier receivables.

What Makes CA-USA Different?

Reputation-Safe Commercial Collections

We pursue the balance without unnecessarily damaging valuable business relationships.

Commercial Credit Reporting

Eligible accounts may benefit from business credit reporting as a non-legal recovery tool.

Contract, Guarantee & UCC-Aware Review

We look beyond the invoice when supporting documents can materially affect recovery options.

Bankruptcy Screening

Accounts are checked before escalation so ordinary collection does not blindly continue against a debtor protected by bankruptcy.

Business Skip Tracing

We help locate businesses and decision-makers when account information has become outdated.

Secure SOC 2 Type II Environment

Sensitive account information is handled through secure infrastructure designed for professional receivables management.

Nationwide Collection Licensing Coverage

CA-USA maintains required collection licenses, registrations and bonds nationwide.

No Recovery, No Contingency Fee

If we do not recover money on a contingency placement, there is no collection commission on the unrecovered account.

FAQs About B2B Commercial Debt Recovery

Does the FDCPA apply to commercial B2B debt?

The federal FDCPA generally applies to debts incurred primarily for personal, family or household purposes and does not ordinarily cover business debts. Commercial collections can still be subject to state laws, licensing requirements, bankruptcy rules, contract law, UCC provisions and other applicable requirements.

When should I send an unpaid B2B invoice to a collection agency?

There is no single deadline for every account. Many businesses consider outside collection after approximately 60–90 days of unsuccessful internal follow-up, but repeated broken payment promises, sudden silence, a defaulted payment plan or signs of financial distress may justify earlier placement.

What documents should I provide to a commercial collection agency?

Ideally provide contracts, credit applications, invoices, statements, purchase orders, proof of delivery or completion, account correspondence, payment history, dispute records, personal guarantees and relevant security or UCC documents. Better documentation generally allows the account to be handled more effectively.

Can CA-USA report an unpaid business account to commercial credit bureaus?

Eligible delinquent commercial accounts may be reportable to participating business credit bureaus when applicable documentation and reporting requirements are satisfied. Commercial credit reporting can provide an additional non-legal incentive for a debtor to resolve an outstanding account.

Can we collect a company’s debt from the owner personally?

Not simply because someone owns or manages an LLC or corporation. A signed and enforceable personal guarantee, sole-proprietor status or another legally recognized basis for personal liability may change the situation. Ownership alone should not be treated as automatic personal liability.

What happens if the debtor business files bankruptcy?

A bankruptcy filing generally creates an automatic stay that stops ordinary collection activity against the debtor for pre-bankruptcy debts. The creditor may instead need to participate in the bankruptcy process, including filing a proof of claim where appropriate.

How can UCC filings affect commercial debt collection?

UCC filings can reveal security interests claimed in business collateral such as equipment, inventory or receivables. When several creditors claim the same collateral, perfection and priority can materially affect their rights. A UCC filing does not prove that a company has money available to pay.

Do B2B collection accounts usually have to go to court?

No. CA-USA first uses professional outreach, documentation review, dispute resolution, negotiation and other appropriate non-legal recovery tools. Attorney referral is considered only when reasonable collection efforts fail and the account supports further escalation.

How much does a B2B commercial collection agency charge?

Commercial collection fees typically depend on the age, balance, complexity and legal status of the account. CA-USA primarily handles commercial collections on contingency, meaning the collection fee is earned only when money is successfully recovered.


Turn Past-Due Receivables Back Into Working Capital

Your company delivered the product, provided the service or fulfilled the contract.

Your team should not spend month after month trying to convince another business to honor an overdue obligation.

CA-USA provides a structured commercial recovery process built around documentation, business intelligence, negotiation, reputation protection and measured escalation.

Firm on the balance. Professional with the people. Legal only when reasonable collection efforts have failed.

Start your recovery process? Contact us

Filed Under: collections

by

Handling the 6 Biggest Collection Agency Sales Objection

Let’s be direct — hiring a collection agency is a big decision. Most businesses don’t do it lightly. It means you’ve tried to collect in-house, you’ve sent reminders, and patience has run thin. At that point, trust becomes everything.

And trust starts with transparency. We’ve heard every concern from business owners, CFOs, and office managers — and the best way to build confidence is to answer those objections head-on, not sidestep them.

Here’s a candid look at the most common objections to hiring a collection agency — and the real answers that smart businesses deserve.

handling collection sales objections


1. The Reputation Question

“Will you harass my customers and ruin my brand?”

This is the number one fear — and it’s valid. Your customers are the foundation of your business. You’ve spent years earning their trust; one wrong conversation can undo that.

The truth is, the “aggressive debt collector” stereotype is outdated. Modern agencies are relationship-focused, not confrontation-focused. Every collector on our team is trained in empathy, negotiation, and professional communication. We don’t pressure — we persuade.

We act as a polite, third-party mediator, not a threat. Our approach protects your brand, your compliance obligations, and often your relationship with the client. Especially for medical and dental offices, where HIPAA and sensitivity are paramount, we view every call as a reflection of your reputation.

A good collection agency doesn’t burn bridges; it rebuilds cash flow without damaging trust.


2. The Cost Question

“Your fees seem high — is it even worth it?”

Fair question. At first glance, a 30–40% contingency fee can seem steep. But the right way to think about it is this: What’s the cost of not collecting anything at all?

An unpaid invoice that’s been sitting for 90 or 120 days isn’t earning you interest — it’s silently costing you. The 100% you keep from uncollected debt is zero.

We only get paid when you do. That means zero risk, zero upfront cost, and potentially thousands in revenue recovered. When you factor in the hours your staff spends chasing overdue accounts — hours that could’ve gone to productive, paying work — our service doesn’t cost you money. It recovers money you were about to lose forever.


3. The In-House Question

“My team can just make the calls.”

That’s true — they can. But should they?

Your office manager, AR clerk, or billing coordinator already wears multiple hats. When they’re spending half their day chasing late payments, they’re not focusing on new revenue, active customers, or patient experience.

Collections require specialized training, skip-tracing tools, legal knowledge, and — most importantly — emotional distance. Debtors respond differently when a neutral third party calls. The dynamic shifts from “I’ll get to it later” to “I need to resolve this professionally.”

Let your team do what they do best — grow your business. Let us do what we do best — get you paid.


4. The Partner Question

“We already have a collection agency.”

Good — that means you understand the value of professional recovery. But the next question is: Are you satisfied?

Most companies have no real benchmark for how their current agency is performing. Are they recovering the right percentage? Are they compliant? Are they protecting your brand voice?

We often suggest a no-risk performance trial — what we call a second placement test. Send us a sample batch of accounts your current agency couldn’t collect. If we don’t recover anything, you’ve lost nothing. But if we outperform them, you’ll see why many businesses re-evaluate who they partner with long-term.

The best partnerships are built on results, not habit.


5. The ROI Question

“How do I know this will actually work?”

This one’s all about trust and data. You want proof — not promises.

That’s why we give our clients full visibility: real-time online reports, detailed activity logs, and recovery dashboards that show exactly where every dollar is in the process.

We also provide industry-specific benchmarks — so you can see how similar businesses in your field (medical, dental, B2B, etc.) have performed. While no agency can guarantee 100% recovery, we can show consistent, data-driven results that turn your uncertainty into confidence.

Transparency builds trust. Trust drives performance.


6. The Compliance & Legal Question (Bonus — and often overlooked)

“Will you keep us compliant and out of legal trouble?”

Absolutely — and this is non-negotiable.

Between Regulation F, TCPA, HIPAA, and state-specific consumer laws, compliance is no longer just an operational checkbox; it’s the backbone of how we collect.

A professional agency invests in ongoing legal updates, call recording, data security, and staff certification. Compliance isn’t just protection for us — it’s protection for you. When you choose a compliant partner, you’re shielding your brand from regulatory risk while maintaining a professional, ethical standard that clients appreciate.


The Bottom Line

Objections aren’t obstacles — they’re opportunities to show what kind of partner you really are.

A great collection agency isn’t just a company that chases money. It’s an extension of your accounts receivable process, your customer service values, and your brand promise.

When you hear these objections, don’t just counter them — answer them honestly. That’s how you build lasting partnerships, recover lost revenue, and turn hesitation into trust.

Filed Under: collections

by

Pennsylvania Commercial Collection Agency for B2B Debt Recovery

Pennsylvania commercial debt can become complicated quickly.

A Philadelphia life-sciences vendor may be waiting on an approved invoice. A Pittsburgh manufacturer may face a sudden dispute over delivered goods. A Lehigh Valley logistics company may be chasing freight charges across related entities. A contractor may have a mechanics-lien deadline running while accounts payable keeps promising payment.

Those files should not be handled with the same script.

CA-USA helps businesses recover overdue B2B accounts across Philadelphia, Pittsburgh, Allentown, Harrisburg, Erie, Scranton, Lancaster and throughout Pennsylvania using professional negotiation, documentation review, business verification, bankruptcy screening, UCC-aware analysis and commercial credit reporting where appropriate.

Attorney referral is considered only after reasonable non-legal efforts fail, the documentation and economics justify escalation, and the client approves it.

Pennsylvania commercial collection agency helping businesses recover B2B debt across Philadelphia, Pittsburgh, Allentown and Harrisburg

CA-USA provides a low cost, compliant, reputation-safe approach, equipped with all 50-state collections coverage, offering free credit reporting, free per-litigation checks, free bankruptcy scrubs, and zero onboarding fees. Secure – SOC 2 Type II compliant. Over 2,000 online reviews rate us 4.85 out of 5.  Over 20 years experience , delivering excellent B2B collection results.

We’ll provide you with the direct mobile number of a dedicated representative, so support is always just a call or text away whenever you need it.

Need a Pennsylvania Commercial Collection Agency? Contact us

See our B2B Commercial Debt Recovery guide for the nationwide approach.


Start With What Created the Debt

A purchase-order balance, consulting invoice, equipment sale and construction receivable may all look like accounts receivable, but the recovery path can differ.

Before escalating, we review contracts, credit applications, purchase orders, invoices, delivery records, payment promises, disputes, personal guarantees and relevant UCC records.

That tells us whether the file is primarily a contract claim, sale-of-goods claim, secured transaction or construction account.

Pennsylvania’s Four-Year Rule — With One Important Exception

Pennsylvania generally gives four years for many contract-based business claims, including obligations founded on a writing. The UCC also generally provides four years for breach of a contract for the sale of goods.

But Pennsylvania has an unusual wrinkle.

A qualifying instrument in writing under seal can potentially carry a 20-year limitation period. That should never be assumed merely because a document looks formal; the actual agreement should be reviewed before relying on the longer period.

Do not determine the deadline from the invoice alone. Determine what document and transaction created the debt.

See our Statute of Limitations for Debt Collection guide for broader timing issues.

UCC Recovery Depends on the Correct Legal Debtor

Pennsylvania’s UCC requires the registered organization’s legal name from its public organizational record. A financing statement using only the debtor’s trade name is not sufficient.

That matters when customers operate through DBAs, affiliated LLCs or related companies.

Before relying on secured-creditor leverage, we want to know:

Which entity signed?
Who received the goods?
Was there a security agreement?
Was the financing statement filed against the correct debtor?

UCC information can help identify creditor priority and collateral issues, but a filing does not prove that the debtor has cash available to pay.

The Owner Is Not Automatically the Debtor

A Pennsylvania LLC’s debt is generally the company’s debt. Members and managers are not personally liable merely because they own or operate the company.

A valid personal guarantee or another legally recognized basis for liability may change the analysis.

The important question is not simply who owns the company, but whether that person actually agreed to be responsible.

Construction Accounts Move on a Different Calendar

A Pennsylvania mechanics-lien claim generally must be filed within six months after completion of the claimant’s work. After filing, written notice generally must be served on the owner within one month, followed by proof of service.

Additional notice requirements can apply on certain projects.

Sending the invoice to collections does not preserve lien rights by itself, so collection and lien strategy should be coordinated while the deadlines remain open.

Pennsylvania Industries Where Documentation Matters Most

Pennsylvania’s current economic strategy emphasizes manufacturing, life sciences, energy, agriculture, and robotics and technology.

For collections, that means recurring accounts involving machinery, laboratory services, energy equipment, software, farm supply, food processing, freight and warehousing.

Recent Recovery Snapshots

Manufacturing Supplier — Recovery 61%

A buyer tried to freeze an entire balance over a quality complaint affecting only part of a shipment. The file was separated into accepted goods, genuinely disputed items and unsupported withholding, allowing negotiations to focus first on the documented undisputed balance.

Related-Entity Account — Recovery 82%

Accounts payable kept redirecting responsibility among related companies. Contract, purchase-order and delivery records were matched to the correct legal entity before business verification and bankruptcy screening. Negotiations then moved directly to the finance decision-maker for that company.

Performance-Based Recovery: Our Fee Follows the Result

CA-USA generally handles Pennsylvania commercial collections on contingency.

Rates typically range from 10% to 45%, depending on balance size, account age, documentation, complexity and debtor condition.

Larger balances and newer accounts generally qualify for lower rates, with pricing confirmed before placement.

A chart showing B2B commercial collection agency fee, that varies by balance and age of debt.

For qualifying fresh commercial accounts under approximately 200 days old and supported by adequate documentation, CA-USA’s internal results can approach ~80% recovery. Results vary and are not guaranteed.

See B2B Commercial Collection Agency Pricing for details.


Pennsylvania Commercial Collection FAQs

How long do I have to collect an unpaid Pennsylvania business invoice?

Many Pennsylvania contract claims generally have a four-year limitation period, including many written obligations and UCC sale-of-goods claims. The transaction and accrual date should be reviewed before assuming the deadline.

Can a Pennsylvania contract really have a 20-year limitation period?

Potentially. Pennsylvania law provides a 20-year period for certain instruments in writing under seal. Whether a particular agreement qualifies should be reviewed rather than assumed.

Does a DBA create problems for Pennsylvania UCC collections?

It can. Pennsylvania’s UCC requires the correct legal debtor name for a registered organization, and a financing statement using only a trade name is insufficient.

Can I collect a Pennsylvania LLC’s debt from its owner?

Not simply because the person owns or manages the LLC. A personal guarantee or another recognized basis for individual liability may change the result.

How long does a Pennsylvania contractor have to file a mechanics lien?

A mechanics-lien claim generally must be filed within six months after completion of the claimant’s work. Separate notice and service requirements also apply.

When should a Pennsylvania B2B account be sent to collections?

Consider early placement when payment promises repeatedly fail, a previously accepted balance is suddenly disputed, communication stops, the debtor changes entities, or financial distress appears.


Recover the Pennsylvania Account While the Facts Are Clear

CA-USA combines contract review, debtor verification, bankruptcy screening, UCC-aware analysis, commercial credit reporting where appropriate and professional negotiation.

See B2B Commercial Collection Agency Pricing and How to Assign Accounts to Collections.

Firm on the balance. Professional with the relationship. Legal only when the account supports it.

Need a Pennsylvania Commercial Collection Agency? Contact Us

Serving Hundreds of Businesses !

Easy to use • Fully Compliant with Federal and State Laws • USA Citizens-Only Team • 24×7 Secure Portal • High Recovery Rates • Over 20 years Experience • Free Commercial Credit Bureau reporting • Low fee • Highly Rated !

blank

Turn Delinquent Accounts from a Liability into a Liquid Asset

You did the work. You delivered the product, provided the service, sent the invoice—and the money still hasn’t arrived. Meanwhile, payroll doesn’t wait. Neither do vendors or growth plans. Aging accounts receivable quietly erode margins, stall expansion, and tie up the time of your most valuable people.

That’s where Collection Agency USA comes in. We are a collection agency that helps Pennsylvania businesses turn overdue invoices into recovered revenue—professionally, compliantly, and without distracting your team from what actually grows your company.

When you partner with us, your delinquent accounts stop being an ongoing headache and start becoming a predictable source of cash flow.

Need a Collection Agency? Contact us


Pennsylvania Debt Facts: Did You Know?

  • 4 Years: The Statute of Limitations on written contracts (breach of contract) in Pennsylvania. If you wait longer than this, the debt becomes legally uncollectible. The clock can “reset” if a partial payment is made.

  • No Commercial Wage Garnishment: Unlike New Jersey or Ohio, Pennsylvania generally prohibits wage garnishment for commercial debts or credit cards. This surprises many creditors. (We use Bank Levies and Property Liens to get you paid instead).

    For standard consumer debts (credit cards, medical bills), wage garnishment is also largely prohibited in PA.

  • 5 Years: The lifespan of a court judgment in PA, which can be revived repeatedly to keep the pressure on.


The Inefficiency and Risk of In-House Collections

Many companies try to “just handle it internally.” It feels thrifty—until it isn’t.

  • High opportunity cost. Every hour your staff spends chasing payments is an hour not spent selling, serving patients, fulfilling orders, or improving operations.

  • Lack of specialization. Your people are experts in your business—not in the psychology, data, and legal nuance of recovery. Effective collections require trained negotiators and disciplined workflows.

  • Compliance landmines. Consumer debt collection is governed by strict rules. The FDCPA and Pennsylvania’s Fair Credit Extension Uniformity Act (FCEUA) set strict standards. A single misstep can lead to penalties. Why take that risk?

Need a Collection Agency? Contact us


Industry-Specific Expertise You Can Count On

We tailor our collection strategies to the industries that drive Pennsylvania’s economy, from the “Eds & Meds” of Philadelphia to the manufacturing hubs of Pittsburgh.

Medical & Dental (Healthcare)
You operate in a complex revenue cycle—coordination of benefits, denials, and patient sensitivity. We bring HIPAA-conscious workflows and the empathy needed to maintain patient relationships—while still resolving balances. Whether you are a large health system in Philadelphia or an independent practice in Allentown, your staff gets relief, and your practice gets paid.

Commercial (B2B)
Business debt is different. Purchase orders, credit terms, and personal guarantees require a different language. Our collectors specialize in B2B disputes, particularly for Manufacturing & Logistics companies along the I-81 corridor. We prioritize preserving viable partnerships where possible and documenting disputes where necessary, so resolutions stick. We also serve the Oil & Gas (Fracking) industry.

Consumer (B2C)
If you manage high-volume consumer AR—retail, rental, or lending—we scale with you. Our data-driven segmentation and multi-channel outreach handle thousands of accounts without losing the personal, compliant touch that moves consumers to act.


The Collection Agency USA Advantage

Superior Recovery Technology
We combine seasoned collectors with modern data. Our team leverages advanced skip-tracing to find debtors who have moved. We use structured, respectful follow-ups—phone, email, SMS, and mail—timed and sequenced for results.

Ironclad Compliance and Peace of Mind
Compliance isn’t a footnote—it’s a framework. We are licensed and bonded to collect in Pennsylvania, and our specialists operate under the FDCPA, FCEUA, and Regulation F. We document what we do, why we do it, and when we did it—so you can sleep at night.

Security: 
We protect client data across Pennsylvania’s healthcare and commercial sectors using enterprise-grade security standards, including 256-bit SFTP transmission, direct API integration, and HIPAA and SOC 2-compliant data handling protocols.

Addressing PA Judgment Execution & Mechanics:
Because Pennsylvania law generally prohibits commercial wage garnishment under 42 Pa.C.S. § 8127, our recovery strategy leverages aggressive post-judgment enforcement mechanisms—including Writs of Execution (Pa.R.C.P. 3102), bank account attachments, and real property liens across Pennsylvania’s 67 county courts.


Flexible, Powerful Collection Solutions

Contingency-Based Collections Simple promise:
We don’t get paid until you do.
Ideal for older or harder-to-collect accounts, our contingency model aligns our incentives with yours. We deploy full skip-tracing, persistent outreach, and skilled negotiators to drive liquidations—while you keep your upfront costs at zero.

Fixed-Fee Programs:
A smart, low-cost first step for early-stage delinquency. We apply the weight of our brand and a disciplined contact cadence—formal demand letters plus compliant initial outreach—at a predictable, flat cost per account. Many balances resolve here, quickly and economically.

Full-Service Legal Forwarding:
When diplomacy needs a stronger lever, we can—with your written authorization—escalate to our Pennsylvania network of vetted creditor-rights attorneys. Since wage garnishment is often off the table in PA, our attorneys focus on Bank Account Seizures and Real Estate Liens to enforce judgments.


Frequently Asked Questions:

The page mentions PA’s FCEUA. Does that only restrict outside collection agencies, or does it apply if we collect our own accounts in-house?

It applies either way. Unlike the federal FDCPA, which generally covers only third-party debt collectors, Pennsylvania’s FCEUA also covers original creditors collecting their own consumer debt, including medical practices billing patients directly. That’s part of why many providers move consumer accounts to a licensed agency early, rather than assuming in-house billing calls are exempt from these rules.

We heard Pennsylvania might be shortening the statute of limitations on debt. Is that already the law?

Not yet. A bill called the Consumer Debt Collection Fairness Act (HB 1731) would cut the current 4-year statute of limitations to 3 years and add strict new documentation requirements for lawsuits, but as of now it’s still moving through the legislature rather than enacted. It’s worth tracking rather than ignoring, since accounts fine to pursue today could land in a much tighter window if it passes.

A former student defaulted on tuition years ago, and we finally got a judgment. Is it still worth pursuing given how much time has passed?

Often yes. A Pennsylvania judgment is valid for 5 years and can be revived repeatedly, so a graduate who couldn’t pay right after leaving school may be far easier to collect from once they’re established in a career. The judgment doesn’t expire just because the debtor’s situation hasn’t caught up yet.


Take the First Step to Improved Cash Flow

Stop letting delinquent accounts dictate your financial health. With Collection Agency USA, you gain a partner focused on one thing: turning past-due balances into present-day revenue.

Ready to recover what you’ve earned? Contact us today to schedule a quick, no-obligation consult. One conversation can change your cash flow for the year.

Filed Under: collections

  • « Go to Previous Page
  • Page 1
  • Page 2
  • Page 3
  • Page 4
  • Page 5
  • Page 6
  • Go to Next Page »

Primary Sidebar

CA-USA: A 4.87 Rated Agency!

Collection Agency Good Reviews

Need a Collection Agency?

Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the plane.

    Recent Posts

    • Utah Commercial Collection Agency for B2B Debt Recovery
    • Virginia Commercial Collection Agency | B2B Debt Recovery | Local
    • What Collection Agencies Do That Restoration Companies Can’t Handle In-House
    • Georgia Commercial Debt Recovery: Delivering Exceptional Recovery
    • Vermont Commercial Collection Agency | B2B Debt Recovery

    Featured Posts

    • Commercial Collection Agency: ~80% Recovery on Newer Debt
    • Georgia Commercial Debt Recovery: Delivering Exceptional Recovery
    • How to Shortlist a Medical Collection Agency in California
    • Commercial Collections Oregon: Recover Cash Without Court
    • Services Collection Agencies Offer That Dentists Can’t Handle In-House

    Copyright © 2026 ·Copyright: CollectionAgencyUSA.com (CA-USA) | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. CA-USA and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements.. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us