• Skip to main content
  • Skip to primary sidebar

Collection Agency USA

collections

by

Recovering Company Equipment/Laptop Cost from Ex-Employees: Why and How to Do It Right

In today’s work-from-home environment, it has become more common for companies to provide laptops and other equipment to their employees. While this arrangement helps ensure smooth workflow and productivity, it can become problematic when employees quit or are laid off but fail to return their company-issued devices.

Despite repeated reminders and attempts to recover the equipment, some ex-employees may become unreachable or simply refuse to cooperate. In such situations, hiring a professional collection agency can be an effective strategy for recovering your property—or the associated costs—while protecting your organization’s reputation and legal interests.

Need assistance? Contact us
Company laptop and asset return checklist illustrating recovery of equipment costs from former employees.

Below is an overview of the risks employers face when attempting to handle returns independently, and how professional collection agencies can help.


The Risks of Handling Recoveries on Your Own

  1. Reputational Damage
    When you directly demand the return of equipment or payment from a former employee, there is a risk of tarnishing your own image. The ex-employee, already disgruntled, may misinterpret your outreach or even claim harassment if they perceive your efforts as overly aggressive.
  2. Legal Complexities
    State and federal regulations govern debt collection practices. An employer that attempts to recover equipment or costs without a clear understanding of these laws may inadvertently break them. This can lead to countersuits, especially if the ex-employee is searching for grounds to take legal action against your organization.
  3. Limited Resources
    Tracing a former employee who has gone off the radar can be a time-consuming process. Most HR or administrative teams don’t have the specialized tools or time to locate someone who is actively avoiding contact, especially if they’ve moved states or changed phone numbers.

Why Hire a Professional Collection Agency

  1. Expertise and Legal Compliance
    Collection agencies follow strict federal and state regulations, ensuring that every attempt to recover property or costs is conducted ethically and lawfully. By engaging professionals, you reduce your risk of violating debt-collection or privacy laws. Our IT asset recovery workflows strictly adhere to corporate cybersecurity and compliance frameworks—including NIST SP 800-88 guidelines for media sanitization and SOC 2 asset management standards.
  2. Preservation of Reputation
    Because a neutral third party is handling the recovery efforts, any negative interaction or confrontation is distanced from your organization. The collection agency’s role shields your reputation from the potential fallout of direct conflict with a former employee.
  3. Emphasis on Professional Consequences
    Former employees often respond more seriously to a collection agency. They understand that persistence, credit bureau reporting, and possibly legal measures could follow if they fail to comply. This sense of urgency can accelerate the return of the company’s assets or the repayment of their costs.
  4. Advanced Recovery Techniques
    Collection agencies employ specialized tools and techniques such as skip tracing—used to locate individuals who have moved without leaving a forwarding address—and litigation scrubs, which identify potential legal risks. By uncovering the ex-employee’s history and current whereabouts, a collection agency can tailor the recovery strategy while advising you on possible legal pitfalls.

The Process of Recovering Costs via a Collection Agency

Let’s consider a practical example: Suppose the cost of the laptop (or other equipment) is $1,000. As an employer, you can place this amount for collection with a professional agency. From there, the collection agency proceeds as follows:

  1. Initial Contact and Negotiation
    The agency will attempt to contact the ex-employee and request either the immediate return of the equipment or the payment of the $1,000. They will use every legal channel available—phone calls, emails, letters—while adhering to all relevant regulations.
  2. Follow-Up and Persistent Efforts
    If initial efforts are ignored, the agency intensifies its efforts. This can include skip tracing if the ex-employee has become unreachable. Depending on state laws and the agency’s agreement with your company, they may also report the delinquency to credit bureaus or send formal notices of potential legal action.
  3. Resolution or Escalation
    The collection agency aims for a swift resolution. Once the ex-employee either returns the equipment directly to you or pays the $1,000, the agency retains its fee (based on the agreed-upon rate) and remits the remainder to you. If, however, the ex-employee still refuses to comply, the agency may recommend legal action, which could involve taking the case to court.

Best Practices for Employers

  1. Clear Equipment Policies
    Establish clear guidelines and agreements regarding company-issued equipment from the outset. Make sure employees acknowledge these policies in writing. This not only helps in recovery but also strengthens your position if legal action is necessary.
  2. Prompt Documentation
    Once you decide to terminate or accept an employee’s resignation, create a paper trail. Document each request for equipment return, including the dates and methods of communication. Detailed records bolster your case and help the collection agency in their efforts.
  3. Consultation with Legal Counsel
    If you are worried that an ex-employee may sue, particularly in cases where they have a history of litigation, consult with legal counsel before taking any collection steps. A well-informed approach can prevent costly lawsuits and reputational damage.
  4. Choose a Reputable Collection Agency
    Not all collection agencies are created equal. Research agencies that specialize in equipment recovery or have a track record with corporate clients. Look for firms that emphasize compliance, transparency, and professionalism in their collection processes.

Frequently Asked Questions

Can we just deduct the laptop’s cost from the employee’s final paycheck instead of hiring a collection agency?

In most states, not without a real fight, and in a handful (California, New York, and Massachusetts among them) it’s essentially off the table no matter what paperwork you have. Federal law under the FLSA technically allows equipment-cost deductions as long as pay doesn’t drop below minimum wage, but state law usually decides the outcome, and most states require a written agreement signed in advance, not just a handbook acknowledgment, authorizing that specific deduction. What’s close to universal: you generally can’t withhold the entire final paycheck until the equipment comes back; that’s treated as its own wage violation even in states that allow a deduction for the item’s value. Given how state-specific this gets, it’s often simpler and safer to pay out full final wages and pursue the equipment’s cost as a separate matter afterward.

At what point does an ex-employee keeping a laptop become theft rather than just an unpaid debt?

Legally, refusing to return company property after being asked can rise to civil conversion (treating someone else’s property as your own) even without criminal intent, and depending on the state and the specific facts, an employer can also file a police report alleging theft. In practice, most employers don’t pursue the criminal route: it’s slower, DAs often decline low-dollar cases, and it can escalate the relationship in a way that makes voluntary return less likely. We generally treat this as a civil recovery matter first, since it resolves faster, and reserve any mention of a police report for accounts where the ex-employee is clearly stonewalling rather than just slow to respond.

IT already remotely wiped and disabled the laptop for security reasons. Does that weaken our claim to the full replacement cost?

Not usually, and it’s often the right call to make regardless. Disabling a device to protect company data is a separate issue from who owns the hardware and who’s responsible for its value; a wiped laptop is still company property that wasn’t returned. If anything, documenting that the device was remotely disabled strengthens the record, since it shows you protected sensitive data rather than leaving stale credentials or files sitting on a device you no longer control. Just be aware that a bricked device can’t be resold or reused if it is eventually returned, so factor that into whether you’re pursuing the hardware itself or simply its value.

The ex-employee says the two-year-old laptop isn’t worth what we’re billing them for. Do we have to negotiate on price?

It’s worth deciding this upfront rather than debating it account by account. Most equipment agreements are written around either the original purchase cost or a depreciation schedule, and spelling that out in the signed policy, rather than picking a number case by case after someone pushes back, keeps it from becoming a negotiation. If the agreement is silent on this, a reasonable depreciated value is usually easier to actually collect than the full original price, since it’s harder for the ex-employee to argue against and less likely to look punitive if the account is ever challenged.


Conclusion

When an ex-employee refuses to return company-issued equipment or reimburse its cost, it can be both a logistical headache and a financial loss. Rather than risk damaging your own reputation or getting mired in legal difficulties, hiring a professional collection agency offers an efficient, compliant, and effective path to recovery. By leveraging their expertise in skip tracing, negotiation, and litigation, a reputable agency maximizes your chances of reclaiming either the device or its value—while ensuring that you remain on solid legal ground.

In today’s ever-evolving work culture, it’s more important than ever to have clear policies, documented processes, and a reliable partner who can navigate the complexities of recovering corporate assets. With these measures in place, your organization can protect its resources, maintain its professional standing, and stay focused on driving business growth.

Filed Under: collections

by

Professional Debt Collection Services in California

Unpaid debts can create significant challenges for businesses and medical practices in California. In a state with high operational costs—from rent to labor—outstanding accounts not only disrupt your cash flow but also consume valuable time. CA-USA (Collection Agency USA) is here to help.

As a leading debt collection agency in California, we specialize in recovering both business and medical debts efficiently, ethically, and in full compliance with state laws.

Why Choose CA-USA for Debt Collection Services?

Expertise in Business and Medical Debt Recovery
At CA-USA, we offer specialized services in business debt collection and medical debt collection. Whether you’re a small business owner grappling with unpaid invoices or a healthcare provider facing delinquent patient accounts, our experienced team is equipped to recover your debts promptly.

In-Depth Knowledge of California Laws (Rosenthal Act)
California is one of the most litigious states in the country. Unlike federal laws, the Rosenthal Fair Debt Collection Practices Act applies strict consumer protection rules to original creditors as well.

  • The Risk: If you try to collect aggressive yourself, you could face legal penalties.

  • The Solution: Our team is well-versed in the Rosenthal Act, the California Consumer Privacy Act (CCPA), and the Hospital Fair Pricing Act. We ensure all our collection efforts are fully compliant, protecting your business from legal pitfalls.

Compassionate Approach to Medical Debt Collection
For medical professionals, maintaining patient relationships is paramount. We approach medical debt collection with sensitivity and respect. We help California providers use tools like medical liens and state offset programs to recover unpaid debts effectively without compromising patient trust.

Need a local Collection Agency? Contact us


California Debt By The Numbers

  • 4 Years: The Statute of Limitations on written contracts in California. If you wait longer than this, the debt becomes legally uncollectible.

  • 10 Years: The lifespan of a court judgment in California (which is renewable). We can enforce judgments long-term.

  • 10% Interest: The statutory interest rate you may be entitled to on unpaid judgments in California.

  • Spanish Support: With over 28% of California speaking Spanish at home, our bilingual collectors are essential for effective communication and resolution. Se Habla Español.


Benefits of Partnering with CA-USA

Improved Cash Flow
Recovering unpaid debts is crucial for sustaining a healthy cash flow. Our effective collection methods increase the likelihood of timely recoveries, allowing you to reinvest in your business or practice without financial constraints.

Time and Resource Efficiency
Managing debt collection internally can be a drain on your staff’s time. By entrusting CA-USA with your debt recovery needs, you free up your team to focus on core business activities while we handle the intricacies of the collection process.

Legal Protection
Our adherence to California’s strict debt collection laws minimizes your exposure to legal risks. We conduct all collection activities ethically and legally, safeguarding your business from potential lawsuits.

Cost-Effective Solutions
We offer flexible pricing models, including fixed fee ($15 an account) and contingency-based fees services (20% to 40% of amount collected). No Recovery, No Fee. You only pay when we successfully recover your debts, making our services a risk-free choice. We also offer fixed fee services.


Our Proven Debt Collection Process

1. Detailed Account Evaluation
We start by thoroughly assessing your delinquent accounts to understand each debtor’s situation. We use “skip-tracing” technology to locate debtors who may have moved to avoid payment.

2. Professional Communication
Our trained agents reach out to debtors using effective communication techniques. We send compliant written notices and make professional phone calls that encourage repayment while maintaining dignity.

3. Legal Escalation When Necessary
If initial efforts don’t yield results, and the balance warrants it, we can escalate the matter through legal channels. We work with a network of California attorneys to file suit, obtain judgments, and enforce wage garnishments where allowed.

4. Transparent Reporting
We keep you informed with regular updates and detailed reports via our secure online portal, so you’re always aware of the progress we’re making.


Serving Diverse Industries Across California

We don’t just serve “California”—we understand the unique regional economies of the state:

  • Los Angeles & Southern California:

    • Healthcare: Hospitals, Urgent Cares, and Cosmetic Surgery practices.

    • Entertainment: Recovering vendor invoices and contract disputes.

  • San Francisco & The Bay Area:

    • Tech & SaaS: B2B subscription recovery and software service invoices.

  • Central Valley (Fresno/Bakersfield):

    • Agriculture & Logistics: Freight bills, equipment leasing, and farm supply debts.

  • Small and Medium-Sized Businesses: Retailers, manufacturers, and contractors statewide.

Take Action Before the Clock Runs Out

Don’t let unpaid debts hinder your success any longer. The clock is ticking on the 4-year statute of limitations. CA-USA – Collection Agency USA is ready to assist you in recovering what’s rightfully yours.


Frequently Asked Questions

Does California’s Rosenthal Act protect only consumers and patients, or does it cover B2B and commercial debt now too?

For decades, just consumer debt — money owed for personal, family, or household purposes. That changed on July 1, 2025, when SB 1286 extended Rosenthal-style protections to cover certain commercial debt as well, specifically business-purpose debt up to $500,000 owed or guaranteed by a California-based debtor. In practice, that means the harassment, deceptive-practice, and communication restrictions long applied to consumer and patient accounts now extend, in a scaled-back form, to B2B receivables too. If your business has been collecting commercial invoices in California the same way you always have, this is a genuinely new compliance layer worth checking against, not just a rule that already applied to someone else’s patient accounts.

What does the Hospital Fair Pricing Act actually require before a patient account can go to collections, and does it apply to us?

The Act specifically covers hospitals and emergency physician groups, not every medical practice. Where it applies, the hospital must screen the patient for charity care or discount-payment eligibility before pursuing collections, wait at least 180 days from the first bill before selling the debt or reporting it to credit bureaus, and avoid liens, wage garnishment, or lawsuits against anyone who qualifies for financial assistance. If you’re a hospital or ER group, that screening and waiting period needs to happen before an account ever reaches us. If you’re an independent clinic, urgent care, or private practice, the Act’s specific mandate doesn’t technically bind you the same way, though checking whether a patient can realistically pay before escalating is good practice either way.

Can a California private school or university withhold a student’s transcript over an unpaid balance?

No, not anymore. California was the first state to ban transcript withholding as a debt-collection tactic, effective January 1, 2020, and the practice is now off the table regardless of how much a student owes. Diplomas and other credentials sit in a slightly different legal position, but the safer assumption for any California school is that leverage tied to withholding a student’s own records won’t hold up. We build collection strategy around payment plans and re-enrollment incentives instead, which tend to work better here than they would have under the old transcript-hold approach anyway.

A restoration company doing wildfire damage repair is owed money, but the client is waiting on an insurance payout or a California FAIR Plan claim before paying. Should we wait too?

Waiting passively is usually the wrong move, even in a legitimate wildfire claim situation. FAIR Plan and wildfire-related insurance payouts are notorious for running long, sometimes for months, especially when a claim gets tied up in a larger disaster event affecting thousands of policyholders at once. An account left alone “until the insurance comes through” often stays unpaid well past the point the check actually arrives. The better approach is a low-key reminder that keeps the account current and creates a paper trail, without escalating hard enough to jeopardize a client relationship that’s already under real financial stress from the disaster itself.

Does a collection agency working in California need to be licensed, and does that apply to commercial debt too?

For consumer debt, yes. California’s Debt Collection Licensing Act has required most third-party debt collectors to hold a license from the Department of Financial Protection and Innovation since 2022, with a handful of exemptions for entities like banks and other already-regulated lenders. For commercial debt specifically, it works differently: the 2025 Rosenthal Act expansion added new conduct rules for collecting business debt, but it did not create a matching licensing requirement, so a collector can be subject to the new commercial-debt conduct standards without needing a separate license for that side of the business. It’s worth asking any agency you’re vetting which side of that line their work actually falls on.

Filed Under: collections

by

How to Switch Collection Agencies Successfully | Sample Withdrawal Letter

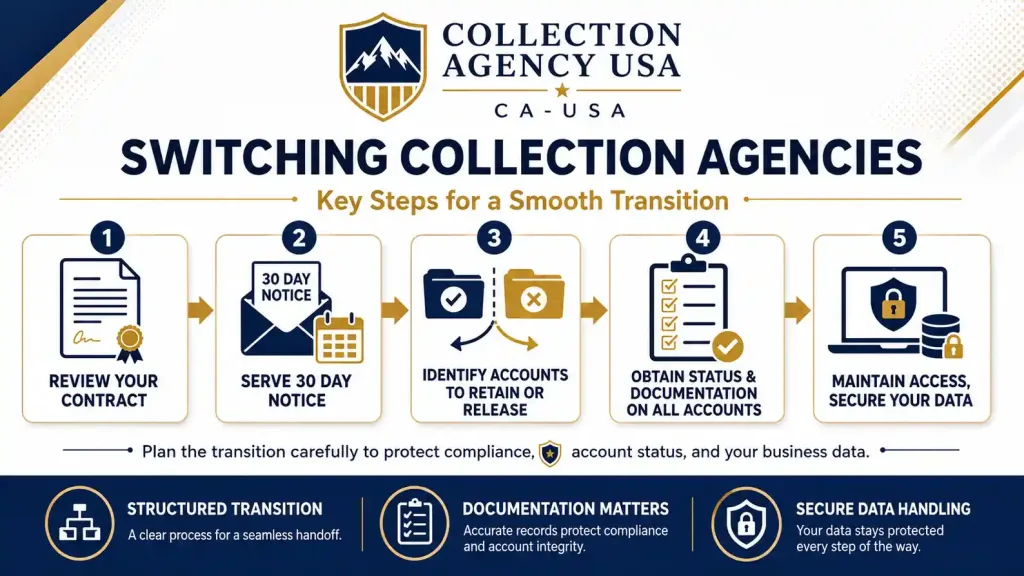
Switching collection agencies checklist showing contract review, 30-day notice, account transfer, documentation, and secure data handling.

If you’re dissatisfied with your current collection agency due to issues like low recovery rates, excessive fees, or poor customer service, it may be time to consider making a switch. Changing your collection agency can seem daunting, but with the right approach, you can smoothly transition to a new partner who better meets your needs. This article will walk you through the steps of changing your collection agency and provide tips on selecting a new one that aligns with your business objectives.

Note: Most collection agencies will agree to close your accounts if you provide them with one month’s notice. They will only retain accounts where debtors have committed to making payments or are already paying in installments. In most cases, the transition is smooth unless your current agency is highly uncooperative.

Additionally, be very careful before hiring a new collection agency, they may look great on the surface but may turn out to be worse than your existing agency.


Need assistance? Contact us


Reasons to Consider Changing Your Collection Agency

Several factors might prompt you to reevaluate your relationship with your current collection agency:

  • Low Recovery Rates: If the agency isn’t recovering debts effectively, it directly impacts your bottom line.
  • Complaints from your Debtors: Harsh tactics and unprofessional behavior can tarnish your company’s reputation.
  • Lack of Transparency: Without clear reporting and communication, it’s difficult to assess the agency’s performance.
  • Excessive Charges: Hidden fees and high contingency rates can erode the value you receive.
  • Poor Customer Service: Inadequate support can lead to frustration and inefficiency.
  • Compliance Issues: Non-compliance with laws like the Fair Debt Collection Practices Act (FDCPA), HIPAA or lacking licenses in certain states can expose you to legal risks.

Steps to Terminate Your Current Collection Agency

Ending your relationship with your current agency requires careful planning to ensure a smooth transition:

  1. Review Your Contract: Check the terms of your agreement to understand the notice period and any termination clauses. Typically, a one-month notice is standard.
  2. Serve Notice: Provide written notice to the agency, clearly stating your intent to terminate the contract.
  3. Identify Accounts to Retain or Release:
    • Retained Accounts: Accounts with active payment plans or verbal commitments from debtors may remain with the old agency until resolved.
    • Released Accounts: All other accounts can be transferred to your new agency.
    • Credit Reported Accounts: If any of your accounts have been credit reported, they should either remain with the old agency or have their credit report entry cleared. If a debtor later disputes the entry and their claim is valid, do you think the old agency will be willing to address the issue after you’ve parted ways?
  4. Obtain Documentation: Request a comprehensive list of all accounts being released and ensure they are marked as closed in the agency’s portal.
  5. Maintain Access: If any accounts are still active, ensure your login credentials remain active until all matters are settled.
  6. Secure Your Data: Ask for sufficient time to download all relevant documents and information before access is revoked.

Sample letter to your collection agency

October 10, 2024

RE: ABC Company (and all our locations – ABC Company 1, ABC Company 2 and ABC Company 3)

To Whom it May Concern,

This letter is to inform you that we have decided to cancel our service with your collection agency (PQRS Collection Agency). We are asking that all of our accounts placed in the last 5 years be closed and returned to us as soon as possible. We intend to assign these accounts to a different collection agency in about 30 days.

We understand that accounts with an active payment plan in place may remain with PQRS Collection Agency. All others should be cancelled immediately. In case any of the accounts that are being withdrawn have been credit reported by you, kindly withdraw those entries from the debtor’s credit report.

Please send either a “.csv” or “excel” list of accounts including the Our Location Name, Reference#, Debtor Name, Signer name (if different from debtor name), Address, City, State, Zip, Phone#, DOB, Placement Date, Last Contact Date, Current Status, Original Balance due and Balance still due. Please add any additional relevant columns (like co-signer, Driver’s License Number, SSN etc. if applicable). For safety, this file needs to be delivered securely to us, or with encryption.

If any accounts have concerning status or are disputed (ex: notice from debtor’s attorney, threatening to sue) or bankrupt, or deceased, etc, kindly indicate in the Current Status column or in an appropriate “Notes” column.

If you are closing all our accounts, kindly allow us 30 days to download our data ( including backup documents we have provided to you).

In case you are holding back a few accounts with active payment plan, do not deactivate our access till those remain with you.

Seeking your cooperation in this matter.

Thank you,

John Doe
Director of ABC Company


Choosing the Right Collection Agency This Time

To avoid repeating past mistakes, consider the following factors when selecting a new collection agency:

1. Prioritize Recovery Rate Over Low Contingency Fees:

While a lower contingency fee might seem appealing, it’s the recovery rate that ultimately determines your net returns.

Example:

  • Agency A: 30% recovery rate, 40% contingency fee.
    • On $100,000 of outstanding debts, you receive $18,000.
  • Agency B: 10% recovery rate, 25% contingency fee.
    • On the same amount, you receive $7,500.

Despite the higher fee, Agency A delivers a better return due to its higher recovery rate.

2. Ensure National Licensing and High Online Ratings

Select an agency licensed in all 50 states to handle accounts regardless of where your debtors reside.

If a debtor moves to another state, your agency should be able to continue collection efforts without legal hindrances.

For example: If your collection agency is licensed only in California where you and majority of your debtors reside, and some of your debtors move to Texas or Nevada, your collection agency will not be able to help you.

Select a collection agency with an online Google rating of more than 4.5 and with over 1000 reviews.

3. Demand Robust Technology and Compliance

  • Online Client Portal: A secure, user-friendly portal allows you to submit and manage accounts, similar to online banking.
  • Data Security: Ensure the agency employs stringent security measures to protect sensitive information.
  • Compliance: The agency should adhere to all relevant laws, including FDCPA and HIPAA, and stay updated with local regulations.

4. Seek Industry-Specific Experience

An agency familiar with your industry can tailor its approach to your debtors.

Recovering for a car dealer, doctor or for colleges, each industry has a very different the way their debtors should be approached.

5. Evaluate Customer Service Quality

  • Dedicated Contact: Having a single point of contact streamlines communication.
  • Support Team: A central client support team can provide additional assistance when needed.
  • Responsiveness: Prompt and effective communication is essential for a successful partnership.
  • Performance-Based Trial Periods — Offer a risk-free “switch” period where new clients only pay commissions on recovered amounts, reducing their hesitation to change agencies.
  • Automated Transition & Client Notifications — Promise automated debtor notification (from old to new collector) to maintain transparency and avoid confusion, ensuring debtors know who is responsible.

Caution:

Be sure to inform your new collection agency about any accounts previously handled by the old agency, and tell them that you have a written confirmation that those accounts have been officially closed by the old agency. Do not assign disputed, bankrupt, or deceased accounts to the new agency; instead, write them off. Additionally, avoid transferring accounts that are over two years old.

Transferring accounts to a new collection agency can be risky if not done carefully. For example, having two agencies pursue the same account is illegal. Ensure all accounts are properly closed before making the switch. There may be other scenarios not covered here, so it’s important to seek guidance from your new agency or an experienced attorney during the transfer to avoid legal complications. If you’re unsure about an account, it’s best to avoid transferring it.

Switching collection agencies requires cooperation from both agencies. If your old agency isn’t providing adequate support, consider leaving existing accounts with them and assigning only new accounts to your new agency. Debt collection is governed by complex laws, and transferring uncertain accounts could pose legal risks for you.

Conclusion

Changing your collection agency is a significant decision that can positively impact your business’s financial health. By carefully terminating your current agency and thoughtfully selecting a new one, you can enhance debt recovery rates, ensure compliance, and improve overall satisfaction. Remember to prioritize recovery rates, ensure national licensing, demand technological excellence, seek industry experience, and value superior customer service in your new agency. With these considerations in mind, you’re well on your way to forging a more productive and profitable partnership.

Need help with switching your collection agency? Contact us

Filed Under: collections

by

Urgent Care Clinics: Recover Unpaid Patient Bills & Deductibles

Urgent care clinics are vital to our healthcare system, offering immediate medical attention without the long waits of emergency rooms. However, the business model of “High Volume, Low Balance” creates a unique financial trap. With the rise of high-deductible health plans, the $50 copay collected at the front desk is often just a fraction of the final bill.

Urgent Care Clinic. Patient Bills Recovery

Consider this: If your front desk misses just $50 in copays or deductibles on 3 patients a day, that totals over $54,000 in lost revenue annually—the equivalent of a full-time nurse’s salary.

At Collection Agency USA, we specialize in the specific needs of Urgent Care. We know that unlike a family practitioner, you may never see that patient again (“transient patients”). We have the tools to recover these one-time debts efficiently and ethically.


CA-USA provides a low cost, compliant, reputation-safe approach, equipped with all 50-state collections coverage, offering free skip tracing, free pre-litigation checks, free bankruptcy scrubs, and zero onboarding fees. Secure – SOC 2 Type II & HIPAA compliant. Over 2,000 online reviews rate us 4.85 out of 5.  Over 20 years experience , delivering excellent medical collection results.

Need a Medical Collection Agency? Contact us


blank

The Hidden Financial Strain: “Deductible Shock”

Unpaid medical bills are a growing concern nationwide. For urgent care clinics, the biggest issue is “Deductible Shock.” Patients often believe their copay covered the visit, only to ignore the bill that comes 30 days later for the remaining deductible. By partnering with a specialized agency, you can hand off these difficult conversations to professionals who know how to explain the balance and secure payment without angering the patient.

Unique Challenges Faced by Urgent Care Clinics

1. Transient “Ghost” Patients:
Urgent Care patients often have no loyalty; they visited you simply because you were the nearest open clinic. This makes them hard to chase.

  • The Solution: We utilize Advanced Skip Tracing. Even if the patient has moved or changed numbers since their one-time visit, our data systems can locate them to ensure delivery of the bill.

2. High Volume of Small Balances
You likely have hundreds of accounts owing $50–$150. Your staff cannot spend hours chasing these small amounts.

  • The Solution: Our Fixed-Fee Letter Service is perfect for this. For a low flat rate (approx. $15/account), we automate the cleanup of these small balances. You keep 100% of the revenue.

    Think of it this way: For less than the cost of a flu shot (approx. $15), we can recover a $150 balance. You keep 100% of the collected funds, often seeing a 10x Return on Investment on these small accounts.

3. Occupational Medicine (B2B Debt)
Many Urgent Cares provide drug screens and physicals for local employers. When a business fails to pay for these services, it isn’t medical debt—it is Commercial Debt.

  • The Solution: We have a dedicated B2B team to recover unpaid invoices from corporate accounts, ensuring your Occupational Health revenue stream remains healthy.


Strategies for Financial Recovery

Implement Clear Payment Policies
Communicate expectations upfront. However, when policies fail, you need a backup plan.

Leverage Technology (24/7 Payments)
Urgent Care patients are used to speed. They open their mail at 7 PM on a Tuesday. We provide 24/7 Mobile-Optimized Payment Portals so patients can pay their balance instantly via their smartphone, preventing “bill fatigue.”

Patient Portal Integration
We can integrate with your billing software. Unpaid invoices can trigger automatic, tiered outreach (email, SMS, soft calls) after a set number of days. Clinics get the benefit of proactive collections without manually chasing each account.

Need a Collection Agency to Recover your Urgent Care Patient Bills? Contact Us

At CA-USA, we specialize in helping urgent care clinics recover outstanding debts efficiently and ethically. Our customized solutions maximize recovery rates while preserving patient relationships. 

Why Partner with a Professional Collection Agency?

A professional collection agency offers:

  • Expertise in Medical Debt Recovery: Employing proven strategies tailored to healthcare.

  • Regulatory Compliance: Ensuring adherence to HIPAA, the No Surprises Act, and the Fair Debt Collection Practices Act (FDCPA).

  • Preservation of Patient Relationships: We handle the “Deductible Conversation” professionally, preserving your clinic’s reputation in the community.

  • Billing Code Knowledge: We understand the difference between a 99214 (Level 4 Visit) and a simple wellness check. Our collectors can explain the ‘Why’ behind the bill to patients, reducing disputes by over 30%.

Success Stories

Clinics partnering with a collection agency have reported:

  • 35% Reduction in Bad Debts: Significant decreases in unpaid bills within months.

  • Occupational Health Recovery: Recovering thousands in unpaid invoices from local businesses for employee screenings.

Contact Us Today If your urgent care clinic is facing challenges with unpaid bills—whether from patients or local employers—contact us today to discover how our collection agency can improve your financial stability.


Frequently Asked Questions

Does the No Surprises Act stop us from collecting a patient’s remaining copay or deductible?

No, not for the ordinary situation most urgent cares are in. The No Surprises Act’s balance-billing protections mainly target emergency care and certain out-of-network ancillary provider bills; they aren’t a shield against a patient’s own agreed-upon cost-sharing (copay, deductible, coinsurance) for an in-network, non-emergency visit. What the Act does add is a Good Faith Estimate requirement for self-pay and uninsured patients, along with a formal dispute process if the final bill ends up substantially higher than that estimate. That’s a compliance step worth getting right on the front end, but it’s a separate question from whether a legitimate deductible balance is collectible.

We see mostly walk-ins. Do we have to give every self-pay patient a Good Faith Estimate before we can bill them?

Not in the way most people assume. The Good Faith Estimate requirement was built around scheduled care, and for genuinely unscheduled, same-day urgent care visits, that specific mandate doesn’t clearly apply the way it does for care booked three or more business days out. Where it does clearly apply is anything scheduled in advance (a follow-up visit, for instance) or any time a self-pay patient actually asks what something will cost — at that point, an estimate is owed, and skipping it can give the patient grounds to dispute the final bill if it comes in well above what they were told. We treat “did the patient ask” and “was this scheduled” as the two questions that matter before pursuing a self-pay balance.

An employer is refusing to pay for a drug screen or physical because they’re disputing the result. Is that a real defense, or a delay tactic?

It’s worth checking, but it rarely holds up as a reason not to pay. The employer contracted for the test to be performed, not for a specific result, so disputing the outcome of a properly administered screen generally isn’t grounds to withhold payment for the service itself. Where it gets legitimate is a genuine chain-of-custody or lab error claim, which usually comes with a specific, documented complaint rather than a vague objection raised only after the invoice arrives. We separate a real quality dispute from a stall tactic before deciding how hard to push a corporate account.

A patient is refusing to pay for a telehealth urgent care visit, claiming they “never really saw a doctor.” How do we handle that?

Treat it like any other disputed visit, with the documentation doing the talking. A completed telehealth encounter — timestamped notes, a prescription sent to a pharmacy, or a documented recommendation to be seen in person if needed — is evidence of a billable service, regardless of whether the patient expected something different from the format. What we watch for is whether the visit was actually completed and documented versus cut short or dropped, since a legitimately incomplete telehealth visit is a different conversation than a patient who got full value and simply doesn’t want to pay for it.

A patient paid with an HSA or FSA card, and now their account administrator is reversing the charge as an “ineligible expense.” Can we still collect?

Generally, yes, since the reversal is a dispute between the patient and their account administrator, not proof the underlying medical debt disappeared. An urgent care visit is about as textbook a qualified medical expense as exists, so an HSA/FSA chargeback is usually a documentation issue on the patient’s end (a missing receipt or itemization) rather than a legitimate denial of the service itself. The balance reverts to being an ordinary patient responsibility once the reversal happens, and we pursue it the same way we would any other unpaid visit.

Filed Under: collections

by

School & University Collection Agency | Tuition Debt Recovery | FERPA Compliant

An unpaid tuition balance is never just a dollar figure — it’s a future alumnus, a family’s referral, or a student who might otherwise re-enroll. We recover what’s owed for K-12 schools and universities using a FERPA-compliant, diplomatic process built to collect the debt without losing the relationship.

FEPRA Complianr collection agency that promotes re-enrolment

A collection agency for schools must be more than just “effective”—it must be diplomatic.

Whether you are a Private K-12 School managing sensitive parental relationships or a University protecting your future alumni network, the agency you hire acts as an ambassador for your institution.

At Collection Agency USA, we specialize in recovering unpaid student debts with a deep understanding of the educational environment. We are FERPA-Compliant, bilingual, and dedicated to recovering revenue without damaging the student-school bond.

Our university collection workflows strictly comply with state-specific public higher education recovery mandates—including state tax offset programs—and adhere to state wage garnishment caps (such as CCPA limits or state-specific prohibitions) when resolving direct institutional tuition debts.


CA-USA provides a low cost, compliant, reputation-safe approach, equipped with all 50-state collections coverage, offering free credit reporting, free pre-litigation review, free bankruptcy scrubs, and zero onboarding fees. Secure – SOC 2 Type II compliant. Over 2,000 online reviews rate us 4.85 out of 5.  Over 20 years experience, delivering excellent collection results.

You’ll receive the direct mobile number of a dedicated representative, so help is always just a call or text away.

Need a Collection Agency? Contact us


The Real Cost of Unpaid Tuition (Why You Must Act)

For many institutions, tuition dependency is at an all-time high. When a student doesn’t pay, the impact goes far beyond a single ledger entry.

  • The “Tuition Gap”: Studies show that carrying just 5% in bad debt can force an institution to raise tuition by 2-3% for compliant families to bridge the gap.

  • The “90-Day Cliff”: In the education sector, the recoverability of a student debt drops by 15% every month after the semester ends. Once a student has transferred or withdrawn, the chance of recovery falls below 40% without professional intervention.

  • Administrative Drain: Your Bursar’s staff spends an average of 12-15 hours per week chasing delinquent accounts—time that should be spent on student services and retention.

Tailored Solutions for Every Institution

We understand that a $50,000 tuition balance requires a different approach than a $200 technology fee. We have segmented our recovery teams to handle the unique needs of your specific institution.

1. Higher Education (Colleges & Universities)

  • Debts Recovered: Unpaid tuition balances, student housing/dorm fees, federal Perkins loans, library penalties, and parking fines.

  • The “Alumni Protection” Approach: We treat every student as a future alumnus. Our collectors use a “Student-First” method that focuses on resolution and financial education rather than confrontation. We aim to recover the debt while preserving the student’s long-term affinity for your school.

  • Encouraging Re-Enrollment: We don’t just collect; we counsel. We explain to students that dropping out often cements their personal liability for the debt. We highlight that by re-enrolling, they may regain eligibility for FAFSA or other government aid, which can often cover the outstanding tuition—solving the financial problem for them and retaining the student for you.

2. Private K-12 Schools

  • Debts Recovered: Overdue tuition, after-care program fees, technology/laptop fees, and extracurricular dues.

  • Parental Relations: For K-12, the “debtor” is a parent. We act as an extension of your business office, sending professional reminders that maintain your standing in the parent community while ensuring bills are paid.


Academic Calendar Integration

We don’t just call; we coordinate with your Registrar and Business Office to leverage your academic cycle.

  • The “Transcript Hold” Strategy: We advise on the timing of placing holds on transcripts or diplomas to maximize leverage during our collection calls.

  • Semester Breaks: We ramp up “soft” communication during winter and summer breaks when students are working and families are planning for the next term, often securing payment plans before classes resume.


100% FERPA Compliance & Data Security

Schools need more than just results; they need absolute security.

  • FERPA Ready: We sign confidentiality agreements to strictly adhere to the Family Educational Rights and Privacy Act (FERPA).

  • GLBA Compliant: We protect financial aid data in accordance with the Gramm-Leach-Bliley Act.

  • Data Security: Our secure online portal ensures that sensitive student PII (Personally Identifiable Information) is encrypted and protected at every stage of the transfer process.


Our Recovery Options: From “Nudge” to “Negotiation”

Phase 1: Early Intervention (Fixed-Fee)

  • Best For: Recent delinquencies (tuition installments, lab fees) or “soft” reminders before the next semester.

  • How it Works: We send a series of 5 diplomatic written notices on our agency letterhead.

  • The Benefit: You pay a low flat fee (approx. $15/account). The student/parent pays you directly. You keep 100% of the recovered funds. This effectively motivates payment without the need for phone calls.

Phase 2: Intensive Collections (Contingency)

  • Best For: Withdrawn students, old tuition balances, or ignored Phase 1 letters.

  • How it Works: Our specialized education collectors begin phone negotiations. We offer flexible payment plans and dispute resolution.

  • The Cost: No Recovery, No Fee. We only get paid a percentage of what we collect.


Top Concerns of Schools (And How We Solve Them)

1. Reputation and Relationships Concern: Harsh tactics could damage the school’s image or viral social media posts. Solution: We use a “soft-touch” model. We record every call and monitor our team to ensure professionalism that aligns with your educational values.

2. Legal Compliance Concern: Violating FERPA or FDCPA laws. Solution: Our compliance officer ensures every action meets federal and state standards. We take on the regulatory burden so you don’t have to.

3. Handling Disputes Concern: Students claiming they “didn’t attend” classes or withdrew early. Solution: We are experienced in handling common education disputes (e.g., withdrawal dates vs. refund policies) and can explain the ledger clearly to students to secure payment.

Partner with an Education Specialist

Don’t trust your student accounts to a generic agency. Choose a partner that understands the value of education.

Outsourcing collections to our agency ensures your team can stay focused on academics and student services, while we manage the time-consuming process of recovering overdue accounts efficiently and professionally.

Delivering exceptional results for Schools Nationwide: Contact us


Frequently Asked Questions

Should we require a student to pay off their old balance before letting them re-enroll, or could that backfire?

It can work as leverage, but it’s worth thinking through both sides before making it a blanket policy. A payment-before-re-enrollment requirement often gets immediate results from students who genuinely intend to come back, since they need the seat more than they need to keep the cash. But for students on the fence, an inflexible balance-first policy can just push them to enroll somewhere else instead, turning a recoverable account into a permanent write-off. What tends to work better is treating re-enrollment itself as the negotiating chip — a payment plan that lets the student register now while paying down the old balance alongside current tuition — since a returning, paying student is worth more to the institution than a one-time collected balance from someone who never comes back.

Is it still legal to withhold a student’s transcript over unpaid tuition?

It’s much more limited than it used to be. As of July 2024, federal Title IV regulations bar institutions from withholding transcripts for any semester in which a student received federal financial aid, once that semester’s balance is paid, even if the student owes money on other terms. On top of that, at least a dozen states (including California, New York, Colorado, and Illinois) have banned or sharply restricted transcript holds as a debt-collection tactic altogether, regardless of federal aid status. Diploma withholding sits in a grayer area and isn’t addressed by the federal rule, but is still worth checking against your state’s specific law before using it as leverage. We build our recommended strategy around what’s actually still enforceable for your institution’s aid mix and state, rather than defaulting to a hold that may now carry regulatory risk.

The parents of one of our K-12 students are divorced, and their custody agreement says the other parent is responsible for tuition. Can we still collect from the parent who signed our enrollment contract?

Generally, yes. A private custody or divorce decree is an agreement between the two parents — it doesn’t automatically bind your school, which isn’t a party to it. Liability for tuition almost always follows whoever signed your enrollment or tuition contract, regardless of what the parents privately agreed to divide between themselves afterward. If the paying parent wants to pursue the other parent for their share, that’s typically a matter for them to resolve through family court, not something your collection process needs to sort out. We still note any custody details a family raises, since it can affect tone and strategy, but it doesn’t change who the account legally sits with.

Filed Under: collections

by

Medical Collections: Why a Systematic Approach is so Important?

Priceless Advice:

  • How to hire a collection agency for your medical practice or hospital and maximize results cost-effectively?
  • Solution: Begin the collection process with fixed-fee written demand letters, regardless of what the collection agency representative recommends. This will initiate the collections process in an amicable manner, protect your reputation and maximize returns.

blank

CA-USA provides a low cost, compliant, reputation-safe approach, equipped with all 50-state collections coverage, offering free credit reporting, free bankruptcy scrubs, and zero onboarding fees. Secure – HIPAA & SOC 2 Type II compliant. Over 2,000 online reviews rate us 4.85 out of 5.  Over 20 years experience, delivering excellent collection results.

You’ll receive the direct mobile number of a dedicated representative, so help is always just a call or text away.

Need a Collection Agency? Contact us


Collecting medical debts is a highly sensitive task, governed by strict government regulations, privacy laws like HIPAA, and stringent credit reporting restrictions. While experienced collection agencies understand the necessity of treating patients respectfully and adhering to all compliance & legal requirements, there’s an even more critical aspect that demands your attention.

For a medical collection agency to work effectively on your behalf, it’s crucial to manage the process systematically. Simply handing over debts and allowing the agency to operate as they see fit may lead them to use methods that benefit their interests over yours. This could negatively impact your profits and reputation. In this article, we will tell you how to hire and use a medical collection agency effectively, any why you should always start collections with fixed-fee services instead of contingency-fee services.

Your collection agency should act as an extension of your front desk. We prioritize ‘Patient Retention‘ over ‘Aggressive Tactics,‘ ensuring your reputation remains 5-star.


Timing Is Crucial

The most critical factor in determining how much money you will recover is how quickly you submit accounts to a collection agency. We strongly recommend submitting accounts for collection between 60 to 90 days after the first default. After three months of reminders, your staff may lose motivation to continue pursuing non-paying patients, who might believe they can evade payment altogether. Waiting any longer is like throwing money away.


Begin with Fixed-Fee Collection Demand Services

For medical debts, it’s essential to start with a Fixed-Fee Collection Demand Service rather than immediately resorting to collection calls.

Frankly, collection agencies barely profit from fixed-fee services, but it’s an excellent cost-effective option for you.

blank

Fixed-fee collection demands are a patient-friendly way to recover debts, providing ample time for patients to pay. They receive five written notices every ten days, which helps them avoid the discomfort of speaking directly to a collector. Sending these five demands costs about $15, and since they’re sent on a medical collection agency’s letterhead, they carry significantly more weight than notices sent from your office. Patients pay you directly. If you attempted to send these demands yourself, the cost could be $50 to $100 or more when all expenses are considered. This approach is not only cost-effective but can also become  a zero-cost service if you write it off as a business expense.


Transition to Collection Calls with Care

If written demands have been unsuccessful and the debt remains outstanding, it makes sense to proceed to Collection Calls, which are more direct. By this point, you’ve given your patients sufficient opportunity to settle their debts amicably, now a diplomatic yet a slightly-firm approach is required.

Accounting Tip: Your accounting treatment can remain separate from collection activity. Consult your accounting professional regarding when a receivable should be classified or written off for financial or tax purposes.


Key Qualities to Look for in a Medical Collection Agency

When selecting a medical collection agency, consider the following important factors:

  • Nationwide Licensing & HIPAA Compliance: Ensure the agency is licensed to operate nationwide and fully compliant with HIPAA regulations.
  • Fixed-Fee Written Demand Services: The agency should offer fixed-fee written demand services as a starting point for collections, averaging $15 per account. There should not be any fee on top of that and patients must be instructed to pay you directly.
  • Secure Online Client Portal: A secure portal allows you to monitor and submit accounts conveniently. They should also be easy to use, and backed by a single point of contact who acts as your customer service representative.
  • Litigious Patient Scrub: The agency should perform a litigious patient scrub to avoid pursuing patients who have a history of suing businesses like yours, unless the balance owed is significant.
  • No On-Boarding Fees and Complimentary Services: Look for agencies that do not charge on-boarding fees and offer free bankruptcy screening and credit reporting. Our collections strategy ensures that No Surprises Act guidelines are also followed. Medical debt credit reporting is subject to the FCRA, applicable state laws, and current credit-bureau reporting policies. Because these requirements continue to evolve, medical accounts should be reviewed for reporting eligibility before furnishing information.
  • Bilingual Services and Extensive Experience: The agency should be bilingual and currently serving over 500 medical and dental offices.
  • High Online Ratings: An average online or Google rating of over 4.5 stars with more than 1,000 reviews indicates reliability and customer satisfaction.

Need a good Medical Collection Agency? Contact us


Before Sending a Medical Balance to Collections, Verify the Bill Is Collectible

Check:

  • Insurance processing is complete
  • Patient responsibility is accurate
  • Required adjustments have been applied
  • Good Faith Estimate requirements were addressed where applicable
  • There isn’t an active No Surprises Act dispute
  • The patient’s identity/contact information is correct
  • No bankruptcy prevents ordinary collection
  • Documentation supports the amount due

Essential Due Diligence When Evaluating Agencies

Verifying Security and Compliance

When evaluating collection agencies, look beyond verbal assurances by requesting written documentation of their security protocols, compliance certifications, and data protection standards.

Benchmarking Recovery Rates

Rather than relying solely on handpicked client references, ask for the agency’s overall average recovery rate across their healthcare portfolio. As a general industry benchmark, reputable agencies typically achieve:

  • Over 50% recovery for accounts assigned within 180 days

  • ~35% overall average across varied account ages

  • Under 15% recovery for older, harder-to-collect accounts

Evaluating Client Track Record

Inquire about prominent healthcare and commercial clients they serve. Long-standing partnerships with established organizations are a strong indicator of reliability, compliance, and consistent performance.


Act Promptly

Time is of the essence in medical collections. Implementing a systematic approach not only enhances your recovery rate but also ensures compliance with all legal and ethical standards. Don’t leave your collections to chance—take control to protect your finances and maintain strong relationships with your patients.


FAQ’s

1. When should a medical practice send unpaid patient balances to collections?
Many practices consider outside collections after roughly 60–90 days of unsuccessful internal follow-up, especially after insurance processing is complete and the patient balance has been verified.

2. Can a medical bill be sent to collections while insurance is still processing it?
Generally, the practice should first complete insurance processing and confirm the patient’s actual responsibility. Sending an unresolved or incorrectly calculated balance to collections can create avoidable disputes.

3. What should a medical practice verify before assigning a patient balance?
Confirm insurance adjudication, contractual adjustments, patient responsibility, billing accuracy, contact information, bankruptcy status, prior disputes and any applicable No Surprises Act requirements.

4. Does HIPAA allow a medical provider to use a collection agency?
Yes. HIPAA recognizes debt collection as a payment activity. When a collection agency handles protected health information as a business associate, appropriate agreements and safeguards are required.

5. Can a disputed medical bill still be sent to collections?
A disputed balance should be reviewed before collection. If a federal patient-provider dispute resolution process is active, the provider may not move the bill into collections and existing collection activity must pause.

6. Can medical debt still be reported to credit bureaus in 2026?
Yes, some unpaid medical debt can still appear. Current CFPB guidance says unpaid medical debt over $500 and more than 365 days delinquent from the date of service may appear on credit reports, subject to applicable law and bureau policies. The CFPB’s broader medical-debt reporting ban was vacated in July 2025.


Conclusion

Medical collections require a careful balance of urgency, respect, and legality. By acting promptly and starting with a Fixed-Fee Collection Demand Service, you increase your chances of recovering debts while minimizing costs and preserving patient goodwill. Be proactive, demand transparency from your medical collection agency, and focus on methods that serve your best interests.


Reviewed by Collection Agency USA — 20+ years of debt recovery experience

Filed Under: collections

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 3
  • Page 4
  • Page 5
  • Page 6
  • Go to Next Page »

Primary Sidebar

CA-USA: A 4.87 Rated Agency!

Collection Agency Good Reviews

Need a Collection Agency?

Kindly fill this form.
We’ll get in touch with you

    Please prove you are human by selecting the tree.

    Recent Posts

    • 2027 B2B Promise-to-Pay Index: Payment Promise Benchmarks & Methodology
    • Utah Commercial Collection Agency for B2B Debt Recovery
    • Virginia Commercial Collection Agency | B2B Debt Recovery | Local
    • What Collection Agencies Do That Restoration Companies Can’t Handle In-House
    • Georgia Commercial Debt Recovery: Delivering Exceptional Recovery

    Featured Posts

    • Washington Commercial Collection Agency for B2B Debt Recovery
    • What Collection Agencies Do That Restoration Companies Can’t Handle In-House
    • Medical Collections: Why a Systematic Approach is so Important?
    • Recovering Company Equipment/Laptop Cost from Ex-Employees: Why and How to Do It Right
    • Ohio Commercial Collections Built for B2B Owners Who Value Relationships

    Copyright © 2026 ·Copyright: CollectionAgencyUSA.com (CA-USA) | This content is provided for general informational purposes only and should not be considered legal advice. Collection laws and requirements may vary by state, account type, documentation, debtor status, and specific facts. Please consult qualified legal counsel for guidance regarding your particular situation. CA-USA and its authorized collection partners service accounts in accordance with applicable federal and state collection requirements.. Visit our home page to know more about us.

    X
    Need a Collection Agency?
    Contact Us