Need a commercial collection agency in Georgia for unpaid B2B invoices? CA-USA helps businesses recover past-due commercial accounts across Atlanta, Savannah, Augusta, Columbus, Macon, and throughout Georgia. Our approach combines reputation-safe negotiation, contract and invoice review, UCC-aware commercial collection practices, bankruptcy screening, business skip tracing, and commercial credit reporting—without unnecessarily damaging valuable customer or vendor relationships.
We focus first on professional communication and negotiated resolution. Attorney referral is considered only when reasonable collection efforts have failed, the documentation and balance support further action, and you approve the escalation. Accounts are placed through a secure SOC 2 Type II environment, with dedicated support and zero onboarding fees.
CA-USA provides a low cost, compliant, reputation-safe approach, equipped with all 50-state collections coverage, offering free credit reporting, free pre-litigation check, free bankruptcy scrubs, and zero onboarding fees. Secure – SOC 2 Type II compliant. Over 2,000 online reviews rate us 4.85 out of 5. Over 20 years experience, delivering excellent B2B collection results.
Need a Georgia Commercial Collection Agency? Contact us
Why Georgia B2B Collections Require a Commercial Strategy
Georgia’s commercial economy is broad and interconnected. Atlanta is a major technology, fintech, cybersecurity, logistics, and professional-services center. Savannah and Brunswick connect manufacturers and distributors to global trade. Aerospace, automotive and EV manufacturing, agribusiness, food processing, energy, life sciences, and advanced manufacturing create complex supply chains across the state.
That means an unpaid Georgia business invoice may involve more than a simple past-due balance. It can involve purchase orders, milestone billing, subscription agreements, retainage, delivery disputes, personal guarantees, secured interests, or a customer that is still valuable to your company.
Commercial debt should therefore be handled as a business problem, not as a larger version of consumer debt. For a broader overview of this distinction, see our guide to B2B commercial debt recovery.
Performance-Based Commercial Collection Pricing
CA-USA uses a contingency-based commercial collection model. If we do not recover money under the contingency service, there is no collection commission. Rates generally range from 10% to 45% depending on factors such as account balance, debt age, placement volume, documentation, and case complexity.
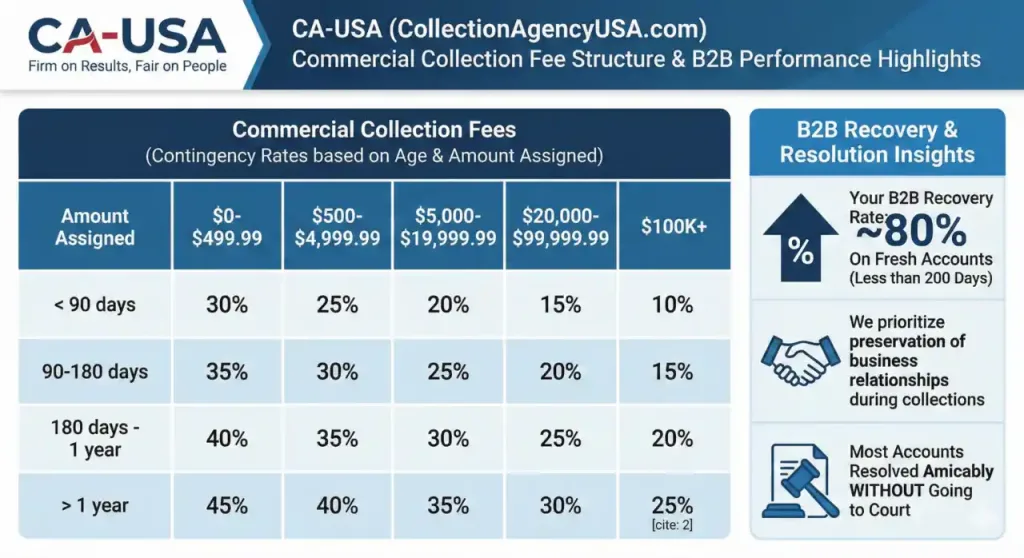
Larger, newer, well-documented balances may qualify for lower contingency rates. Older accounts, small balances, international matters, or accounts requiring additional legal work can carry higher rates.
For a deeper comparison of commercial collection pricing, see what a B2B commercial collection agency should charge.
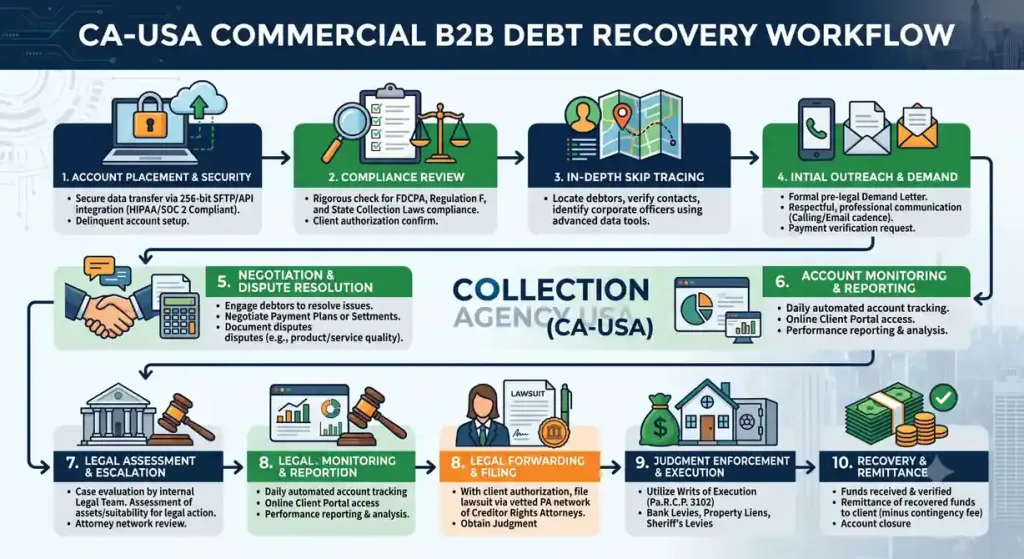
The 7-Step Commercial Debt Recovery Framework in Georgia
Step 1: Contract, Invoice & UCC Review
We begin with the signed agreement, invoices, purchase orders, credit applications, payment terms, guarantees, account statements, dispute history, and relevant supporting records. When security interests or financed goods may be involved, we also review available UCC information. The goal is to understand what is documented before choosing a collection strategy.
Step 2: Bankruptcy, Business & Address Verification
Before escalation, we screen for bankruptcy and verify the debtor’s legal business identity, operating status, addresses, ownership information, and available corporate records. This helps prevent wasted effort on dissolved entities, incorrect debtor names, or accounts affected by bankruptcy restrictions.
Step 3: Reputation-Safe Business Outreach
Initial outreach is professional, firm, and factual. We contact the people who can actually resolve the account—accounts payable, controllers, finance leaders, owners, or executives—while avoiding unnecessary hostility that could destroy an otherwise valuable business relationship.
Step 4: Dispute Resolution & Negotiation
If the debtor raises a dispute involving delivery, scope, quality, pricing, credits, contract terms, or payment timing, we identify the specific issue and separate genuine disputes from simple delay. When appropriate, negotiated payment arrangements can resolve the balance while preserving future business.
Step 5: Commercial Credit Reporting — Where Eligible
Eligible delinquent business accounts may be reportable to participating commercial credit bureaus, subject to documentation, reporting requirements, and the circumstances of the account. When appropriate, commercial credit reporting can create an additional non-legal incentive for a solvent company to address a delinquent balance.
Step 6: Management & Documentation Review
Before recommending legal escalation, the account is reviewed again for documentation strength, debtor status, dispute history, collectability, prior negotiation efforts, and the economics of further action. Legal should be a reasoned business decision—not an automatic next step.
Step 7: Attorney Referral — Only as a Last Resort
If reasonable collection efforts and negotiations fail, and the documentation, balance, and collectability support further action, attorney referral may be considered with your authorization. Litigation is a final escalation after non-legal recovery options have been exhausted, not the standard starting point.
Georgia Commercial Collection Deadlines
Written Contracts: Generally Six Years
Georgia generally provides a six-year limitation period for actions on simple written contracts, running from when the obligation becomes due and payable. The rule does not apply to every type of commercial transaction, so the underlying agreement still matters.
Open Accounts and Certain Other Contracts: Generally Four Years
Actions on open accounts, implied promises, and certain contracts not signed by the party being charged are generally subject to a four-year limitation period.
Sale of Goods Under Georgia’s UCC: Generally Four Years
A breach-of-contract claim involving the sale of goods generally falls under Georgia’s UCC four-year limitation period. This can matter for manufacturers, distributors, equipment suppliers, food processors, automotive vendors, and other companies selling goods rather than services.
Construction Accounts May Have Much Shorter Lien Deadlines
Georgia mechanics’ lien rights can involve a separate 90-day filing deadline after completion of work or furnishing of materials, followed by additional enforcement deadlines. Sending an account to collections does not automatically preserve lien rights, so construction and material-supplier accounts should be reviewed promptly.
For a general explanation of time-barred debt and state limitation periods, see our statute of limitations guide. Specific Georgia deadlines can depend on the contract, transaction, accrual date, tolling issues, and other facts.
Trust & Compliance
Commercial Credit Reporting
Eligible delinquent business accounts may be reported to participating commercial credit bureaus where appropriate, adding a non-legal incentive for resolution while supporting responsible business-credit practices.
Contract, Invoice & UCC Review
We review available contracts, invoices, purchase orders, guarantees, security interests, and relevant UCC information before choosing a recovery strategy. A UCC search can reveal competing secured interests and help clarify whether another creditor may already have priority in particular collateral.
Bankruptcy Screening
Accounts are screened for bankruptcy before escalation. A bankruptcy filing can trigger an automatic stay that restricts ordinary collection activity, so a delinquent account should not be pushed forward as though no filing exists.
Business Skip Tracing & Entity Verification
We use lawful business skip-tracing tools and available corporate records to help confirm legal entities, current addresses, operating status, ownership information, and other details needed to reconnect with difficult-to-locate debtors.
Secure Portal & SOC 2 Type II
Accounts and supporting documents are submitted through a secure online environment backed by SOC 2 Type II controls designed to protect sensitive business and account information.
Nationwide Licensing & Compliance
CA-USA maintains required collection licenses, registrations, and bonds where applicable nationwide and uses established procedures designed to support applicable federal and state collection, privacy, and data-security requirements.
Attorney Referral — Only as a Last Resort
Our first priority is reputation-safe communication, documentation, dispute resolution, and negotiation. Attorney referral is considered only after reasonable collection efforts fail, the account supports escalation, and the client authorizes the next step.
Industries We Serve in Georgia
Technology, SaaS, Fintech & Cybersecurity
Subscription, licensing, implementation, payment-processing, professional-service, and enterprise contract balances across Atlanta’s technology and fintech ecosystem.
Logistics, Freight & Distribution
Carrier, warehouse, drayage, 3PL, freight, shipping-client, and supply-chain receivables connected with Savannah, Brunswick, Atlanta, and Georgia’s extensive rail and highway network.
Automotive, EV & Advanced Manufacturing
Equipment, component, tooling, industrial-service, supplier, and commercial contractor balances supporting Georgia’s expanding automotive, battery, EV, and manufacturing base.
Aerospace & Defense
Engineering, aircraft-component, maintenance, tooling, supplier, subcontractor, and commercial-service receivables in one of Georgia’s major export and manufacturing sectors.
Agribusiness & Food Processing
Packaging, equipment, ingredient, cold-chain, transportation, agricultural-service, and supplier balances across Georgia’s large farming and food-processing economy.
Life Sciences & Healthcare Vendors
Strictly B2B balances involving laboratories, pharmaceutical and medical-device companies, healthcare suppliers, practices, facilities, and service providers.
Construction & Trades
Subcontractor, equipment-rental, material-supplier, retainage, and project-related commercial balances where contract documentation and separate lien deadlines may be important.
Professional & Business Services
Unpaid invoices involving staffing, consulting, accounting, marketing, IT services, legal support, engineering, and other contract-based business services.
Why Our Commercial Collection Process Matters in Georgia
A UCC Filing Error Changed Creditor Priority
In a Georgia bankruptcy case involving financed equipment, one creditor filed a UCC financing statement using a debtor name that did not match the debtor’s official Georgia identification. The court found the name seriously misleading because the filing did not appear under Georgia’s standard search logic. Another creditor that later filed correctly was therefore treated as having the superior perfected interest.
Our approach: We do not assume that a security agreement or UCC filing automatically creates the priority a creditor expects. Debtor names, filing details, perfection, competing liens, and the underlying security documents can materially affect commercial leverage. Relevant UCC information should be reviewed before relying on secured-creditor rights.
A Personal Guarantee Changed the Recovery Path
In a 2024 Georgia commercial lease dispute, a business tenant stopped paying and later filed bankruptcy. The bankruptcy stayed the claim against the company, but the creditor continued its case against the individual who had signed a personal guaranty. The Georgia Court of Appeals held the guaranty enforceable when it was read together with the contemporaneously signed lease, although some damages issues were sent back for further review.
Our approach: A company bankruptcy does not automatically answer every recovery question. Personal guarantees, contemporaneous agreements, contract language, damages documentation, and the identity of the liable parties should be reviewed before deciding what options remain.
Frequently Asked Questions
Does Georgia’s Fair Business Practices Act generally apply to ordinary B2B debt disputes?
Georgia’s Fair Business Practices Act primarily focuses on consumer transactions involving goods, services, or property mainly for personal, family, or household purposes. Ordinary business-to-business transactions generally fall outside that primary consumer focus. Commercial collections still remain subject to applicable contract law, bankruptcy restrictions, UCC rules where relevant, and other federal and state requirements.
How long can we pursue an unpaid business invoice in Georgia?
Georgia generally provides six years for simple written contracts, while open accounts and certain other contractual claims generally have a four-year period. Contracts for the sale of goods generally fall under Georgia’s UCC four-year limitation period. The correct deadline depends on the agreement, transaction, accrual date, and other facts, so older B2B accounts should be reviewed individually.
How does Georgia’s UCC affect a commercial collection?
Georgia’s Uniform Commercial Code can affect sales of goods, security interests, financing statements, lien priority, inventory, equipment, receivables, and other secured commercial rights. We review available contracts, guarantees, security agreements, and relevant UCC information because filing and perfection details can materially affect the options available on a commercial account.
Can an unpaid Georgia business account be reported to a commercial credit bureau?
Eligible delinquent commercial accounts may be reportable to participating business credit bureaus, subject to reporting requirements, documentation, and the circumstances of the account. When appropriate, commercial credit reporting can provide an additional non-legal incentive for a business to resolve an outstanding balance before attorney referral is considered.
Can we pursue the owner of a Georgia LLC personally for the company’s unpaid debt?
Usually not simply because someone owns, manages, or works for the LLC. Georgia law generally provides that LLC members and managers are not personally liable for company obligations solely because of that status. A written personal guarantee or another legally recognized basis for personal liability can materially change the analysis, which is why guarantees and supporting agreements should be reviewed carefully.
When does CA-USA refer a Georgia commercial account to an attorney?
Legal action is a last resort. CA-USA first uses documented outreach, dispute review, reputation-safe negotiation, commercial credit reporting where appropriate, and other non-legal recovery options. Attorney referral is considered only when reasonable collection efforts have failed, the documentation and balance justify further action, collectability supports the expense, and the client authorizes escalation.
Ready to Recover a Past-Due Georgia Business Account?
If a customer, vendor, contractor, distributor, or commercial client has stopped paying, early professional intervention can preserve more recovery options while reducing the amount of staff time spent chasing an old invoice.
If you are preparing a file for placement, our guide to assigning accounts to a collection agency explains the documentation that helps a collector get started.